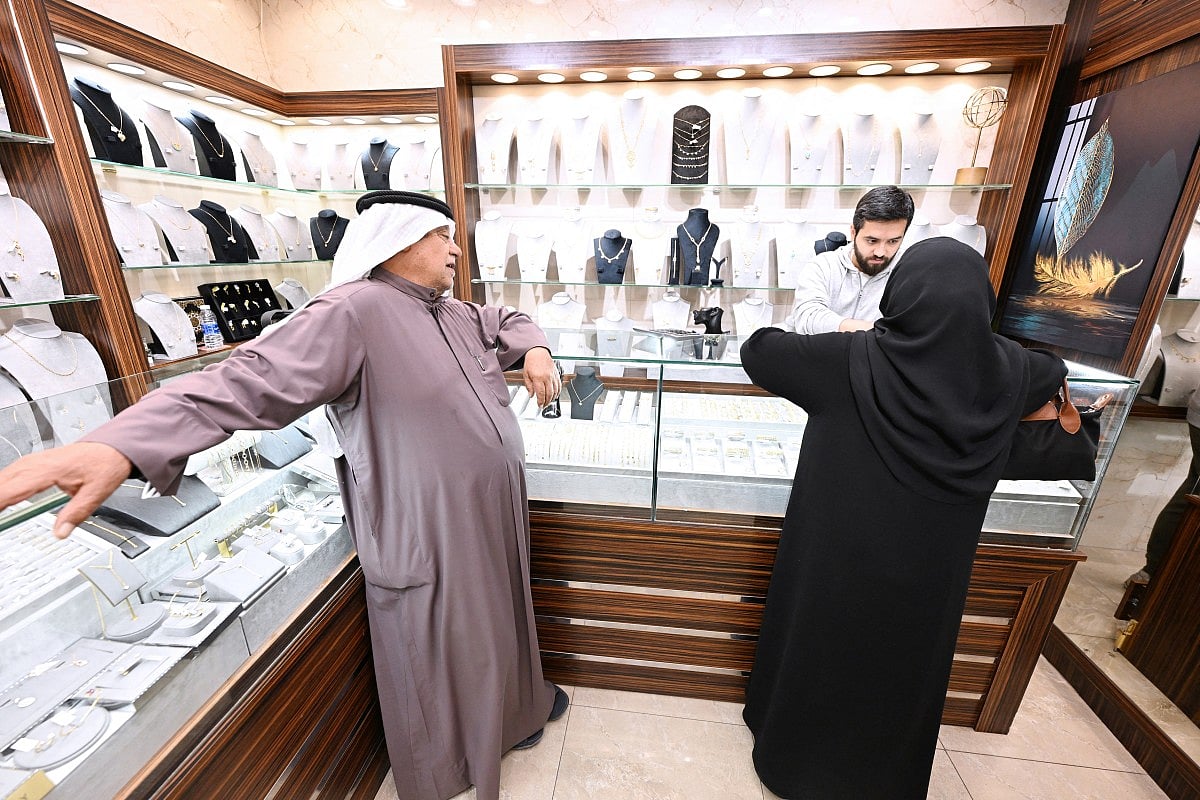
Dubai: Dubai gold prices climbed again on Friday morning, extending a record-setting run that has brought the Dh600 level firmly into view for retail buyers and investors. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
By 8.45 am, the 24-karat rate stood at Dh595.50 per gram, up from Dh591.75 a day earlier. The 22-karat variety rose to Dh551.50 from Dh548, marking another sharp daily gain in what has already been a volatile month for precious metals.
January rally
The speed of the move has been striking. Gold opened the month near Dh520 per gram for 24-karat jewellery. Within the first week, prices pushed past Dh540, before briefly consolidating around the Dh535 to Dh538 range. Mid-month brought renewed momentum, with rates climbing above Dh550 and then accelerating again after January 18.
Over the past five sessions alone, 24-karat prices have surged from around Dh562 to nearly Dh596, while 22-karat has jumped from roughly Dh521 to above Dh551. The cumulative rise since the start of January now exceeds Dh75 per gram for 24-karat gold, reshaping purchase decisions for households planning weddings, savings-linked buying and long-term investment.
Global forces driving local prices
Dubai’s rally mirrors an extraordinary surge in global bullion markets. Spot gold climbed to a record above $4,967 an ounce on Friday and was on track for a weekly gain of almost 8%, supported by a sharply weaker dollar. Silver pushed to an all-time high just below $100 an ounce, while platinum also reached a record.
Gold has now risen about 15% since the start of the year, building on its strongest annual performance since 1979. Heightened geopolitical risks, renewed questions around the independence of the US Federal Reserve and military tensions in multiple regions have pushed investors toward hard assets and away from sovereign bonds and fiat currencies.
This shift has been reinforced by central bank activity. Goldman Sachs Group Inc. raised its year-end gold forecast to $5,400 an ounce from $4,900, citing sustained buying by private investors and official institutions. Poland’s central bank, the world’s largest reported buyer of gold, approved plans this week to add another 150 tonnes to its reserves. India has also reduced its holdings of US Treasuries to a five-year low, redirecting flows toward gold and other alternatives.
Fed uncertainty adds fuel
Market attention has turned to the next leadership choice at the Federal Reserve after US President Donald Trump said interviews for the role of Fed chair have concluded. Expectations of a more dovish appointment have increased bets on further interest rate cuts following three consecutive reductions, a supportive backdrop for non-yielding assets like gold.
A weaker dollar has amplified the move, making precious metals cheaper for buyers using other currencies and encouraging fresh inflows into bullion-backed assets.
Silver volatility spills over
Silver’s rally has added another layer of complexity to the precious metals market. Prices have more than tripled over the past year, driven by heavy retail participation, a historic short squeeze and supply concerns linked to export policy uncertainty in China.
- With inputs from Bloomberg.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.