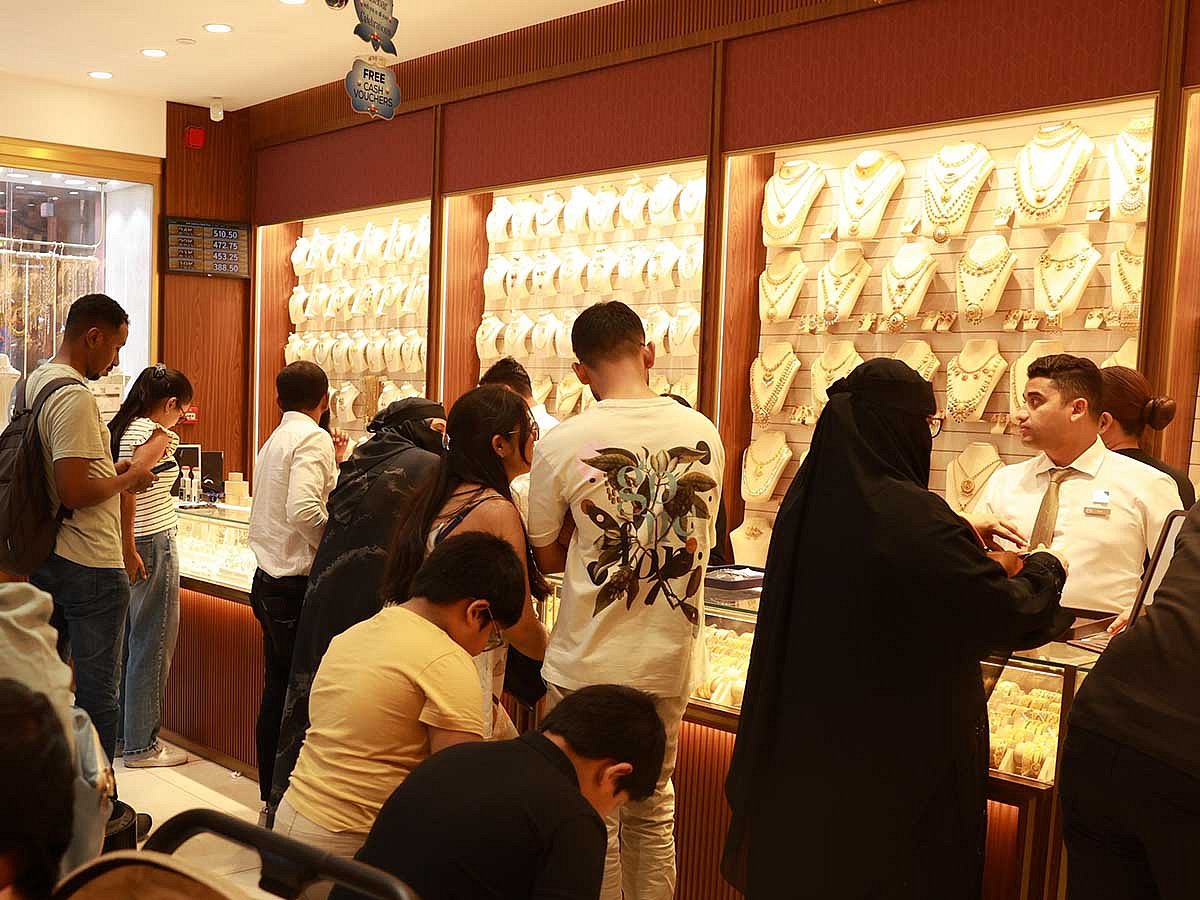
Dubai: Dubai gold prices fell again on Friday morning, giving jewellery buyers a lower entry point after a volatile month that saw rates swing from record highs to their lowest levels in weeks. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
The 24-karat variety stood at Dh482.50 per gram at 8.37am on Friday, down from Dh486 on Thursday. The 22-karat variety, which is more widely used in jewellery, fell to Dh446.75 from Dh450.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
The latest move means 24-karat gold is now Dh60 lower than the June 2 level of Dh542.50, while 22-karat has dropped Dh55.50 from Dh502.25 on the same day. The decline gives UAE shoppers some relief after prices stayed above Dh500 for most of the month.
June rally loses steam
Gold opened June at Dh539.75 for 24-karat and quickly rose to Dh542.50 on June 2, the highest point of the month. Prices stayed elevated in the first week, holding above Dh521 between June 5 and June 8, before slipping to Dh514.25 on June 9 and then falling further to Dh492.50 on June 10.
There was a brief recovery in the middle of the month, with 24-karat moving back to Dh522.25 on June 16, but that rebound did not last. Prices eased to Dh509.25 on June 18, Dh506 on June 22 and Dh498.75 on June 23, before falling below Dh487 this week.
The change is significant for shoppers because every Dh10 move per gram can add up quickly on larger purchases. A 20-gram 22-karat purchase would cost about Dh8,935 at Friday’s rate, compared with Dh10,045 at the June 2 level.
Global gold slips below $4,000
The fall in Dubai prices followed weakness in international bullion, with gold dipping back below $4,000 an ounce and heading for a fourth weekly loss. Spot gold fell as much as 1.1% to near $3,983, reversing a modest gain from the previous session.
The pressure came as a tech-led selloff in Asian stocks added to market volatility, prompting some investors to sell gold to cover losses elsewhere. Bullion has also come under pressure from renewed concerns that US interest rates could stay higher for longer.
The metal’s recent decline marks a reversal from last year’s strong rally, when gold delivered its best annual performance in four decades. Demand for safe-haven assets, geopolitical risks and concerns over fiscal debt had driven investors into gold, but that trade has cooled in recent months.
Dollar strength weighs on bullion
A softer US inflation reading on Thursday gave some support to gold, after the personal consumption expenditures price index rose by 0.4% in May. The data eased some pressure on bond markets, while traders slightly reduced bets on another US rate increase.
Higher borrowing costs remain negative for gold because the metal does not offer interest income. A stronger dollar has added further pressure, making dollar-priced commodities more expensive for buyers using other currencies.
The dollar has gained 1.7% since the latest Federal Reserve meeting, where policymakers signalled support for higher borrowing costs and new chair Kevin Warsh struck a hawkish tone.
- With inputs from Bloomberg.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.