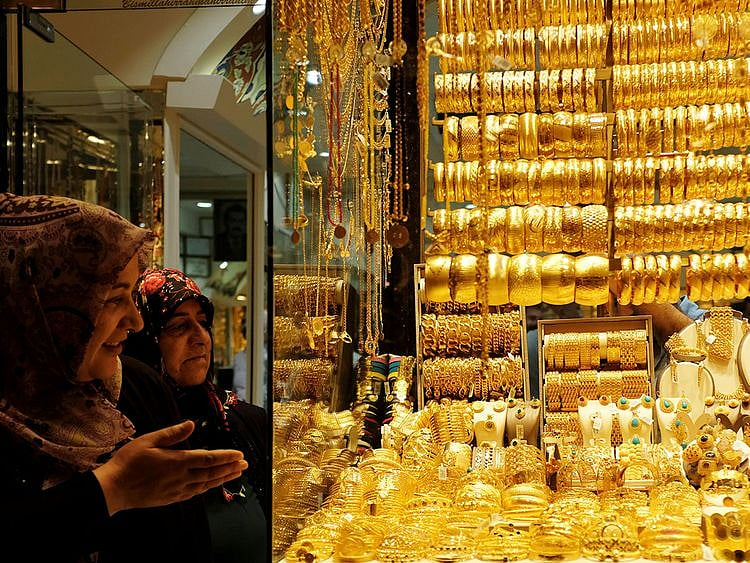
Dubai: Dubai’s gold market has spent the month moving within a relatively tight band, even as global bullion prices swung on shifting expectations around US monetary policy. Retail rates for 24K in the UAE opened November at Dh482.25 a gram and have largely oscillated in a Dh475 to Dh505 range. The lowest point came on November 4 when 24K fell to Dh475.25, reflecting a brief dip in international prices and a stronger dollar. The rally that followed pushed Dubai rates back toward Dh504.75 on November 12, mirroring the global uptick when bullion climbed on safe-haven demand and a pause in dollar strength. From there, prices eased again, slipping into the high Dh480s by mid-month, before stabilising at Dh489.75 on November 18 and 19. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
The month shows three clear phases. The first was a soft, slightly volatile start as 24K moved from Dh482.25 on November 1 to Dh475.25 by November 4, before rebounding sharply to Dh495.50 by November 11. The second was a short-lived spike between November 12 and 13, when 24K touched Dh504.75 and then Dh502.25. The third is the current cooling-off period, where Dubai prices have settled into the Dh485 to Dh493 corridor as traders reassess the likelihood of a December rate cut.
A similar pattern played out in 22K. It began the month at Dh446.50, slipped to Dh440 on November 4, and then climbed steadily to Dh467 by November 12. From there it fell back to the mid-450s and has now stabilised at Dh453.50. The movements in both 24K and 22K show how closely UAE retail rates continue to track global sentiment rather than local demand alone.
Mid-month spike fades as global sentiment softens
Globally, bullion has been trying to find direction. Gold is steady near $4,070 an ounce as traders balance several competing forces. A decline in global equities and concerns about stretched tech valuations have supported safe-haven interest, but that support is diluted by traders unwinding leveraged positions. The market is also recalibrating expectations for US policy. Commentary from Federal Reserve officials has dragged down the probability of a December rate cut from near-certainty two weeks ago to a coin toss now, muting one of the strongest catalysts for bullion. Investors are waiting for the delayed September US jobs report and the release of the Fed’s October meeting minutes, both of which may offer clues on whether the central bank is preparing to reopen liquidity taps. Any sign of easier policy would act as a fresh tailwind for precious metals.
Despite the near-term back-and-forth, the broader picture remains decisive. Gold is still up about 55% this year and tracking toward its strongest annual performance since 1979, helped by robust central-bank buying and continued investor interest in hedging against sovereign and currency risk. The Bank of America survey suggesting that global investors expect gold to deliver the second-best returns next year reinforces how firmly sentiment remains tilted in bullion’s favour.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.