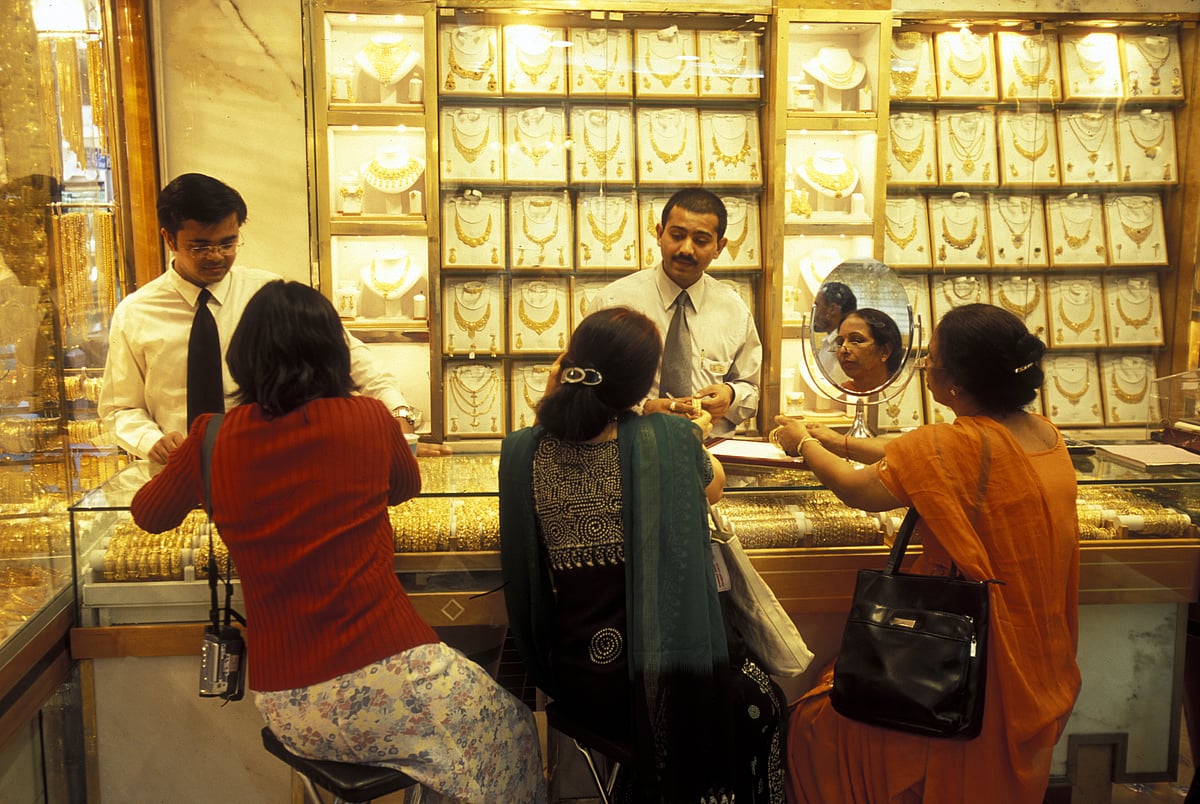
The 24-karat variety was priced at Dh491.75 per gram at 9.18 am on Thursday, down from Dh492.50 on Wednesday, while 22-karat gold stood at Dh455.25 per gram compared with Dh456 a day earlier.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
The latest move marks a steep pullback from levels seen earlier this month, when 24-karat gold opened June at Dh539.75 per gram and 22-karat gold stood at Dh500. Prices then climbed to Dh542.50 and Dh502.25 on June 2 before easing to Dh536 and Dh496.25 on June 3. The highest point so far this month came on June 4, when 24-karat gold reached Dh538.50 and 22-karat touched Dh498.50.
Prices held above Dh520 for several days after that, with 24-karat gold at Dh522.50 on June 5 and Dh521.75 on June 6 and 7. The decline gained pace this week, with 24-karat falling to Dh514.25 on June 9 before slipping below Dh500 by June 10. The drop leaves shoppers looking at prices that are nearly Dh48 lower per gram from the start of the month for 24-karat gold.
Buyers get a lower entry point
The fall below Dh500 is likely to draw attention from UAE residents planning jewellery purchases, especially those tracking prices for weddings, gifting and summer travel. The move also comes after several sessions of global volatility, with gold reacting to fresh geopolitical tension, stronger US economic data and changing expectations around interest rates.
Internationally, bullion swung in choppy trading after the US completed a new round of strikes against Iran, a development that added pressure to markets already concerned about energy supplies and inflation. Tehran’s move to close the Strait of Hormuz to all vessels raised fresh concerns over oil flows, keeping inflation expectations elevated.
Gold initially drew support from geopolitical risk, but that support has weakened as investors focus more on the implications for US rates and the dollar.
US data weighs on gold
Ahmad Assiri, Research Strategist at Pepperstone, said gold’s weakness reflects a change in what markets are choosing to price.
“Gold’s weakness reflects a fundamental shift in what markets are choosing to price. Rather than a signal focus on geopolitical uncertainty surrounding the strait of Hormuz, investors are increasingly reacting to the prospect that US monetary policy moving tighter given the recent way-too-strong NFP figure as well as the CPI print well above the 4% mark.”
The latest US inflation reading showed consumer prices rising 4.2% from a year earlier in May, the fastest pace since 2023, with higher energy prices adding to the pressure. That has made investors more cautious on gold, which usually struggles when yields and the dollar remain firm.
Assiri said the inflation print has strengthened the case for the Federal Reserve to keep policy restrictive.
“Energy-led inflation is now elevated enough to reinforce the case for the Fed to maintain a restrictive monetary policy stance. While the data did not deliver an upside surprise, it continues to support the view that policymakers may need to keep interest rates high, with the possibility of a rate hike this year.”
Higher interest rates tend to reduce the appeal of gold because the metal does not offer a yield. A stronger dollar also makes bullion more expensive for buyers using other currencies.
Hormuz risk feeds inflation fears
The latest Middle East escalation is also being read differently by markets. Instead of driving sustained safe-haven demand for gold, the risk of disruption through the Strait of Hormuz is feeding inflation concerns through higher energy prices.
Assiri said this has become counterproductive for bullion.
“The re-escalating conflict between in the Middle East has become a clear source of inflationary concern and the longer the risk of disruption to shipping through the Strait of Hormuz persists, the higher the pressure on global energy prices.”
He said investors have shifted attention away from traditional safe-haven buying and toward the risk that higher inflation could force the Federal Reserve to stay restrictive or even revive the possibility of rate hikes.
What shoppers should watch next
Gold is now trading close to the psychologically important $4,000 an ounce level in global markets, after falling about 25% from late February levels. Assiri said a sustained recovery would likely need a change in US economic data or a meaningful easing of geopolitical tension.
“While some market participants continue to monitor the $4,100 region as an important technical level, a sustained recovery is likely to require either a meaningful reassessment of US economic data or a material de-escalation in geopolitical tensions.”
Dubai shoppers may continue to see frequent price changes in the near term, with global gold taking cues from oil prices, US inflation data, Federal Reserve signals and developments in the Middle East. The latest drop gives buyers a lower price point than earlier this month, but the market remains sensitive to sudden moves.
- With inputs from Bloomberg.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.