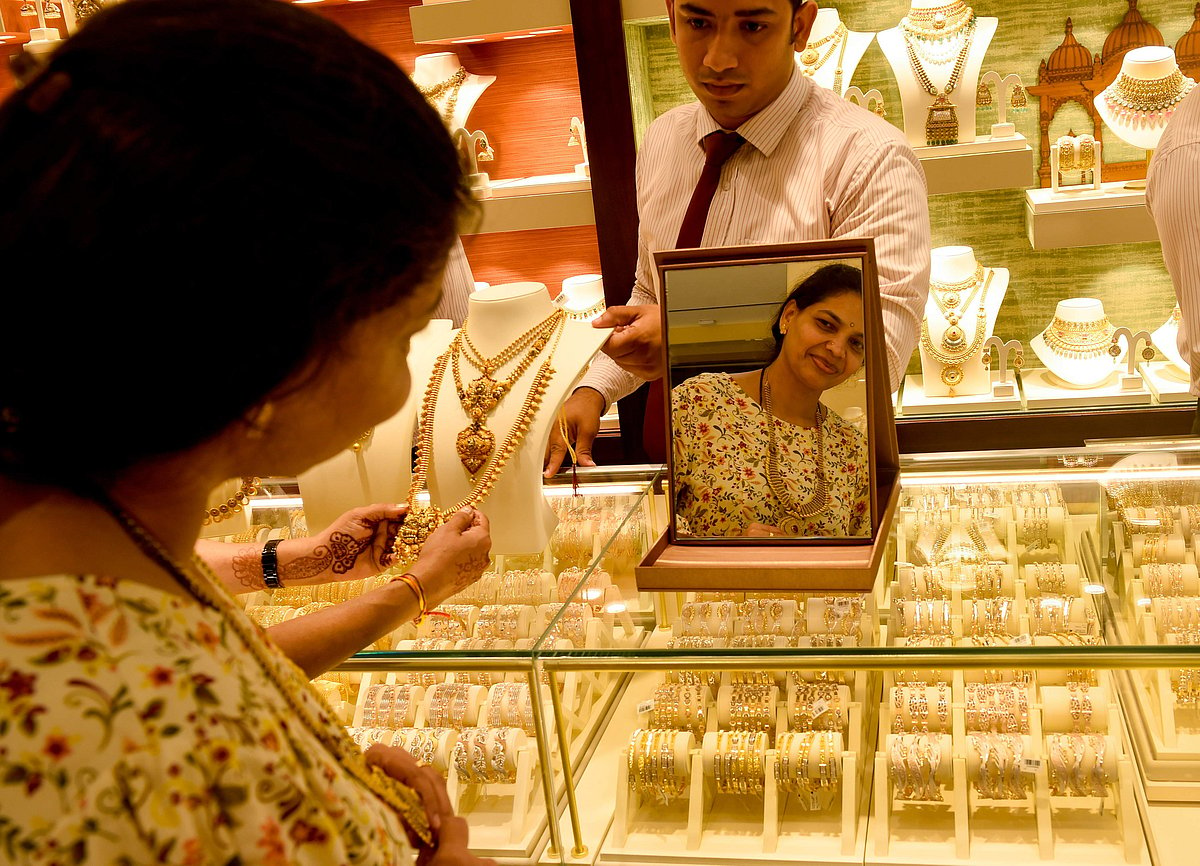
Dubai: Dubai gold prices moved higher early Wednesday, extending a short-term rebound after a sharp correction through March that unsettled buyers and traders alike.
At 8:22 am, 24K gold stood at Dh566.75, up from Dh563.25 a day earlier, while 22K rose to Dh525 from Dh521.50. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
The uptick follows a volatile month where prices dropped nearly 12%, marking the steepest monthly decline since October 2008. That slide has reset expectations across the market, with buyers returning in phases rather than rushing in.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
Peak to pullback
Gold had surged to levels above $4,700 an ounce in recent sessions, recovering from a broad sell-off triggered by rising US Treasury yields and a stronger dollar.
The shift in direction reflects a wider change in market positioning. Investors who once turned to gold for protection during geopolitical stress instead moved toward yield-bearing assets, particularly as expectations of interest rate cuts faded.
Ahmad Assiri, Research Strategist at Pepperstone, said gold’s behaviour through March marked a clear break from its traditional role.
He added that rising yields and a stronger dollar “forced a painful downside repricing of the yellow metal,” with investors moving away from expectations of monetary easing and pricing in tighter conditions.
War outlook shifts sentiment
Recent gains have been supported by signs that tensions in the Middle East may ease, with market attention shifting from immediate conflict risks to longer-term economic implications.
Comments from US President Donald Trump suggesting a potential resolution within weeks have lifted equities and softened the dollar, creating space for gold to stabilise.
Bond traders have also reduced bets on aggressive rate hikes, focusing instead on growth risks tied to the conflict. That recalibration has helped bullion regain some ground, though conviction remains limited.
Buyers weigh timing
Despite the rebound, the broader trend still reflects caution. Prices remain well below mid-March peaks, when 24K gold crossed Dh600, highlighting the scale of the recent correction.
Assiri pointed to deeper structural shifts shaping demand.
“The market chose the yield of the dollar and the volatility of oil over the safety of gold,” he said, noting that capital moved toward assets offering stronger returns during the height of uncertainty.
Also Read
Tokenised gold gains traction as investors shift during market turmoilDubai gold finds footing near Dh550 after month-long declineGold fails to deliver the usual crisis surge. Analysts explain whyThat dynamic is likely to keep buyers selective in the near term. Jewellery shoppers and investors in the UAE are watching for clearer signals on rates and geopolitical stability before committing in size.
Outlook steadies, but not settled
Some global banks continue to maintain a constructive view on gold over the longer term, citing central bank demand and the possibility of rate cuts later this year.
Still, the near-term outlook remains tied to macro signals. Movements in yields, the dollar and energy markets are now playing a more decisive role than geopolitical headlines alone.
- With inputs from Bloomberg.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.