Saudi firms keep hiring even as non-oil growth momentum softens: Riyad Bank PMI
Saudi non-oil PMI eases to 57.4 as prices rise and business optimism turns more cautious
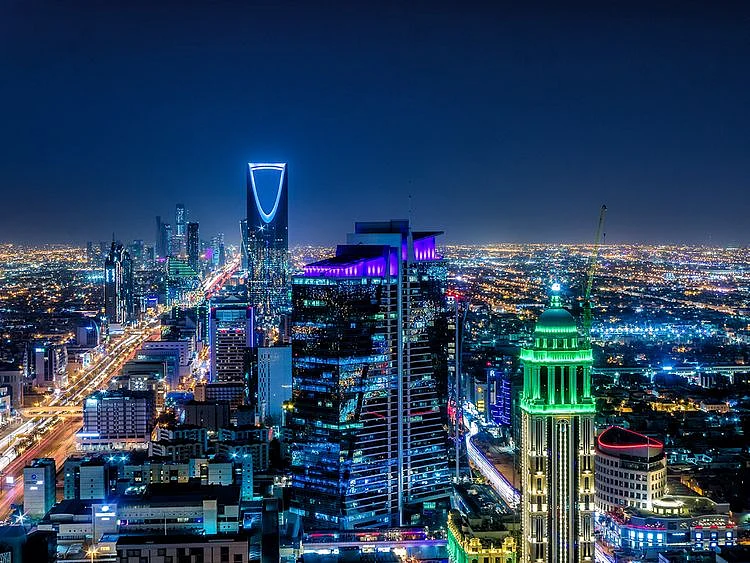
Dubai: Saudi Arabia’s non-oil private sector ended 2025 with solid growth, but the latest Riyad Bank PMI shows momentum easing as firms contend with stronger cost pressures and tougher competition. The headline index fell to 57.4 in December from 58.5 in November, the second monthly slowdown in a row, yet remained comfortably above the 50 neutral mark and slightly above its long-run average of 56.9.
Growth still strong, but pace eases
The December reading confirms the non-oil economy is still in expansion mode, though the rate of improvement is the slowest in four months. Output and new orders continued to rise at a firm clip, but both posted their softest gains since August, suggesting demand is holding up rather than accelerating.
“Saudi Arabia’s non-oil private sector closed the year with a solid expansion, as the headline PMI eased to 57.4 in December, with activity continuing to expand despite some loss of momentum," said Naif Al-Ghaith PhD, Chief Economist at Riyad Bank. "Output growth remained solid, supported by sustained domestic demand, project approvals, and ongoing business investment, even as the pace of growth eased to its slowest since August.”
Demand resilient, exports uneven
Survey panellists reported another strong rise in new orders, helped by improving economic conditions, new client wins, fresh contract awards and targeted marketing campaigns. However, some firms flagged the risk of market saturation, which contributed to a slight cooling in overall order growth and a more cautious view of the year ahead.
“New orders stayed above the expansion threshold, signalling continued demand inflows," added Al-Ghaith. "Export demand recorded a marginal increase for the fifth consecutive month, but the latest rise was the weakest in this sequence, suggesting that external demand remains supportive but uneven. Overall, demand conditions point to resilience rather than acceleration as firms navigate a more competitive environment.”
Hiring continues as backlogs build
Hiring remained a clear positive in December as non-oil firms added staff for another month to keep up with workloads. Employment growth was similar to November and remained strong in historical terms, even as it has cooled from the October peak, underscoring that companies are not pulling back on capacity.
Despite the increase in headcount, backlogs of work rose again, with the rate of unfinished business accumulation hitting its highest level since July. Purchasing activity also picked up, with firms stepping up input buying at the fastest rate in three months and lifting inventories above their recent trend, helped by an improvement in suppliers’ delivery times.
Cost pressures intensify, output prices follow
On the price side, December brought a clearer squeeze on margins. Input costs rose at a faster pace, driven mainly by higher purchase prices for materials and other inputs, even as wage pressures eased to their lowest level in 20 months.
“On the cost side, inflationary pressures increased, led by a rise in input and purchase prices, while staff cost inflation remained contained," Al-Ghaith noted. "Output prices increased at a faster pace and broadly in line with input cost trends. Meanwhile, purchasing activity and inventory accumulation picked up, signalling preparation for sustained demand conditions.”
Most firms chose to pass higher costs on to customers, leading to a more pronounced increase in selling prices during the month. That marks a shift from earlier in the year, when some businesses were absorbing cost rises to protect volumes in a competitive market.
Outlook positive but more cautious into 2026
Forward-looking sentiment softened in December, even though firms still expect growth to continue into 2026. The Future Output Index stayed above the neutral line but dropped to its weakest level since July, reflecting more guarded expectations relative to the series average.
“Looking ahead, business sentiment softened despite remaining positive. The Future Output Index stayed above the neutral mark, indicating expectations of growth into 2026, but fell to its lowest level since July, reflecting more cautious confidence,” Al-Ghaith said.
Concerns about rising market competition and signs of slower order growth are weighing on confidence, even as the underlying picture remains one of expansion supported by domestic demand, project pipelines and ongoing investment. December’s PMI suggests the non-oil economy is still in healthy territory, but entering 2026 in a phase where pricing power, efficiency and differentiation will matter more as growth normalises and competition intensifies.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.