Dubai gold slips as global rally loses steam amid oil shock
Oil near $100 and higher yields slow gold momentum in global markets
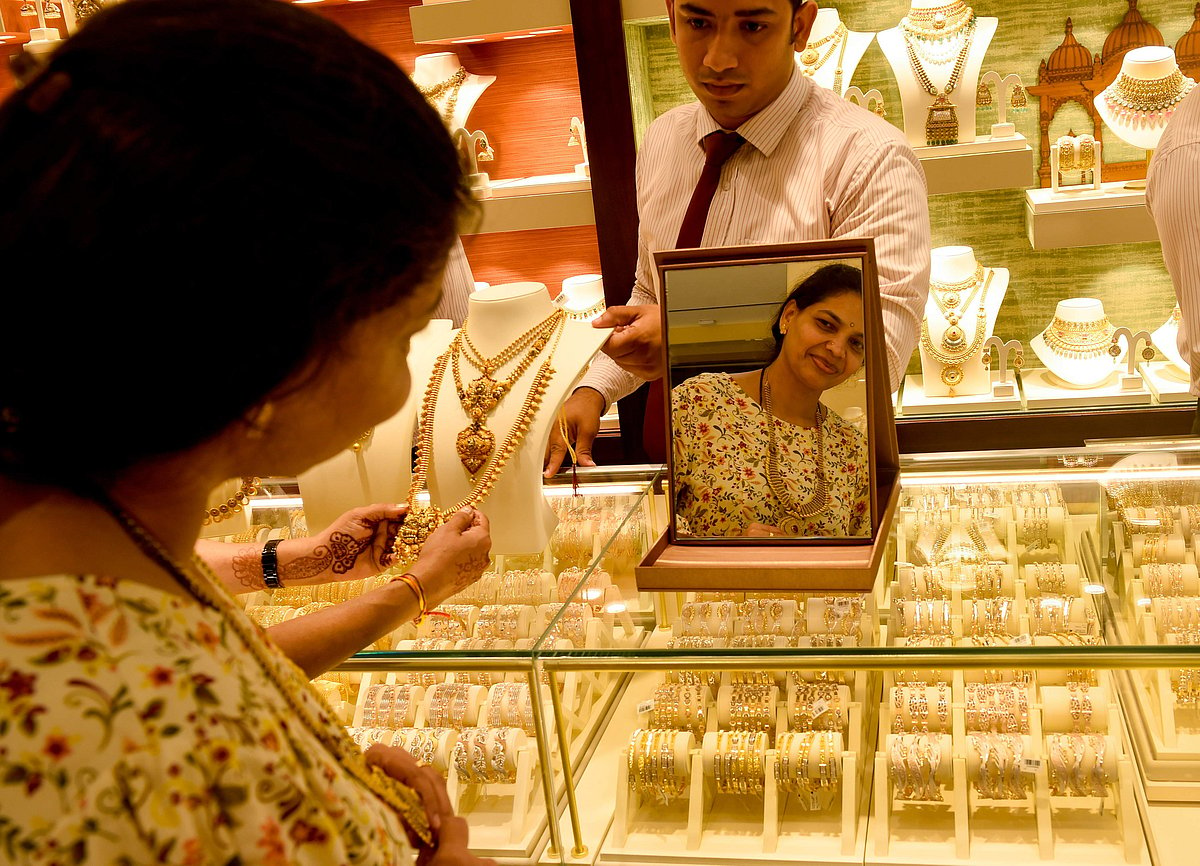
Retail rates in the local market reflected the softer trend. The price of 24-karat gold stood at Dh615 per gram at around 10.30 am, down from Dh617.50 on Thursday. The 22-karat variety slipped to Dh569.50 compared with Dh571.75 a day earlier.
Local prices have fluctuated sharply during the past two weeks as global bullion markets reacted to geopolitical tensions, volatile energy markets and shifting expectations around interest rates.
Stay updated: Get the latest faster by downloading the Gulf News app - it's completely free. Click here for Apple or here for Android. You can also find it us on the Huawei AppGallery.
Choppy price movements
Gold prices in Dubai have swung widely since the start of the month, reflecting the turbulence seen in international markets.
Rates climbed early in March when 24-karat gold moved above Dh640 per gram and 22-karat gold approached Dh594. The rally proved short-lived and was followed by a series of pullbacks. Prices retreated to around Dh614 to Dh620 through the first half of the month before slipping again in the latest session.
Retail demand in the UAE often tracks global bullion trends closely, meaning sudden moves in international markets quickly translate into changes in shop prices across Dubai’s gold souks and malls.
Global market pressure
International bullion markets have faced strong cross-currents this week. Gold rose on Friday but still remained on course for a second weekly decline after a two-day drop earlier in the week.
Spot bullion traded above $5,100 an ounce, recovering part of its losses while oil prices hovered near $100 a barrel following sharp swings in energy markets.
Momentum in the gold rally has slowed since the conflict between the US, Israel and Iran intensified almost two weeks ago. Disruptions to shipping through the Strait of Hormuz have triggered one of the largest shocks to global oil markets in recent years.
Higher crude prices have added to inflation concerns and reduced expectations that central banks will cut interest rates in the near term.
Interest rate outlook
Rising yields have also weighed on sentiment toward precious metals. US Treasury yields climbed to their highest levels since August, reflecting stronger economic data and fading expectations of imminent monetary easing.
Traders now see virtually no chance of a rate cut at the next Federal Reserve meeting and only about a 70% probability of a reduction later this year.
Higher borrowing costs generally reduce the appeal of gold since the metal does not offer interest income.
Volatility in other markets has also affected bullion trading. Some investors have sold gold to cover losses and margin calls elsewhere in their portfolios during the recent period of financial market turbulence.
Despite the latest pullback, gold remains significantly higher for the year. Bullion has gained about 18% since January and has largely held above the $5,000-an-ounce threshold.
- With inputs from Bloomberg.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.