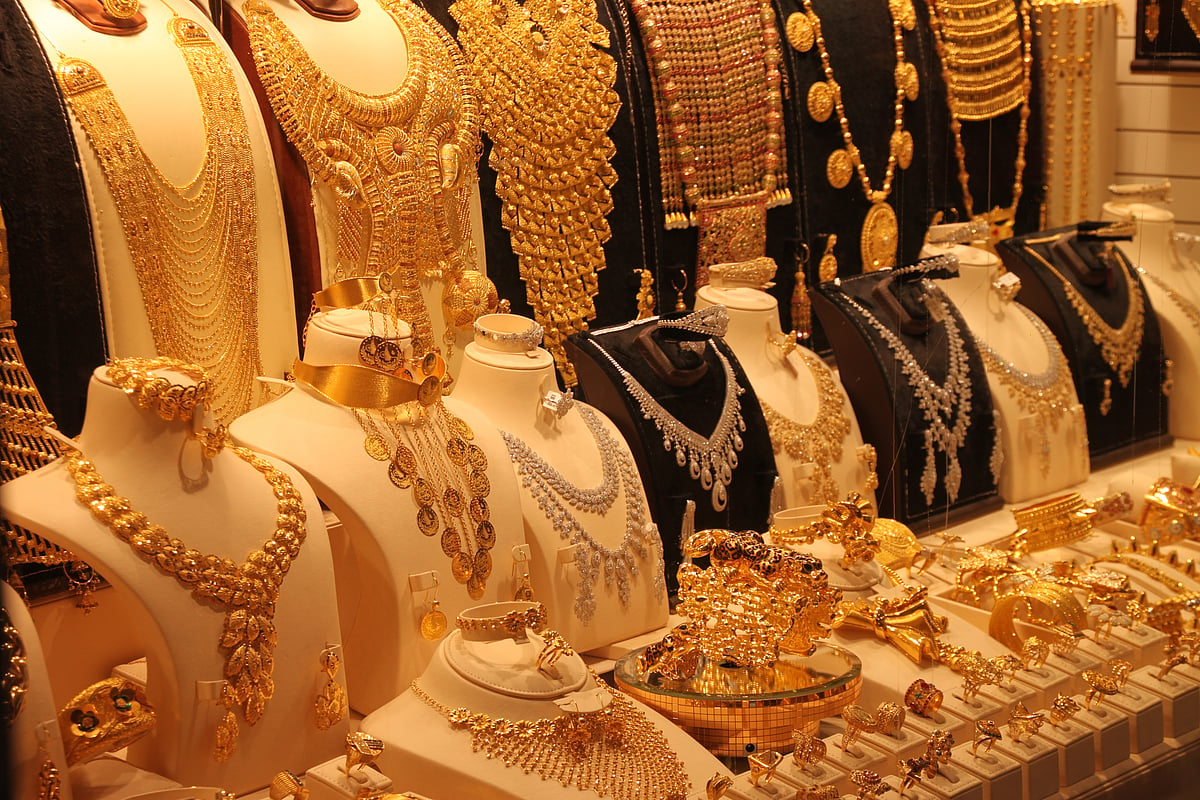
At 9:40am, 24K gold was trading at Dh563.50, up from Dh563.00 on Thursday, while 22K rose to Dh521.75 from Dh521.25 a day earlier. The modest gains reflect a market that is stabilising after weeks of volatility, with buyers and investors watching closely for signs of direction.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
A volatile month reshapes price levels
The latest move comes after a turbulent March that saw gold retreat from record highs before finding a floor toward the end of the month.
Prices had climbed to a peak of Dh628 per gram for 24K gold on March 10, before extending gains to Dh617.50 on March 12 and remaining elevated above Dh600 through mid-March. Momentum then shifted sharply, with prices falling to Dh561.50 by March 19 and continuing lower toward the Dh520–Dh540 range in the final week of the month. By March 30, gold had dropped to Dh541.75, before rebounding slightly into early April, where it is now holding around Dh563 levels.
The pattern points to a market that has moved from strong upward momentum into a consolidation phase, with recent gains suggesting some stability returning.
Global pressures keep gold in check
Analysts say the recent pullback from global highs reflects competing forces shaping gold’s direction.
Linh Tran, Market Analyst at XS.com, said: “Gold has pulled back from the peak around the $4,800 level after failing to sustain its upward momentum. However, the current correction remains largely technical in nature rather than signaling a reversal of the broader trend.”
She pointed to persistent pressure from elevated US Treasury yields and a strong dollar, which have weighed on prices, even as geopolitical risks continue to support demand for safe-haven assets.
Recovery signals underlying demand
Despite the recent volatility, analysts say the broader outlook for gold remains constructive, with signs that selling pressure has eased.
“The rebound has also been supported by dip-buying activity, particularly after a period of aggressive liquidation," Tran said. "This reinforces the view that the market is moving toward a rebalancing phase rather than establishing a new downtrend.”
She added that gold is likely to trade within a wide range in the near term, with support around $4,600 and resistance near $4,800, suggesting that prices may remain steady before any renewed upward move.
What this means for buyers
The current phase offers a window of relative stability for UAE shoppers after weeks of sharp swings, though prices remain well below recent peaks.
The shift from rapid declines to smaller daily moves indicates that the market is settling, with buying activity gradually returning at lower levels. Analysts say this phase could persist in the near term, with gold holding within a defined range as global signals around inflation, interest rates and geopolitical risks continue to influence sentiment.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.