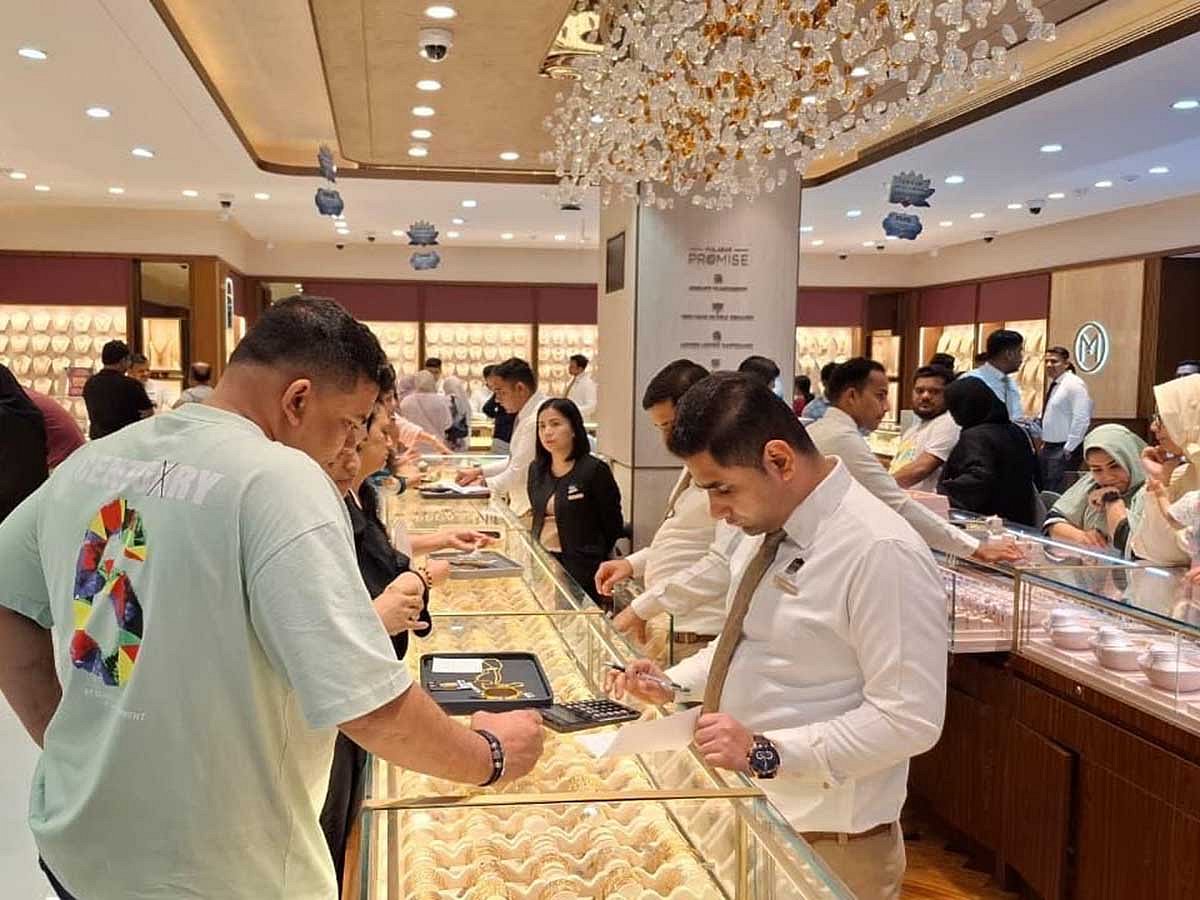
Dubai: Dubai gold prices moved higher on Friday morning, reversing part of the previous day’s decline and drawing renewed attention from buyers tracking short-term swings.
At 9:22 am, 24-karat gold was priced at Dh535.50 per gram, up from Dh529.25 on Thursday. The 22-karat variant rose to Dh495.75 from Dh490, reflecting a steady recovery after a brief pullback.
Stay updated: Get the latest faster by downloading the Gulf News app - it's completely free. Click here for Apple or here for Android. You can also find it us on the Huawei AppGallery.
A month of sharp swings
The broader trend over the past month shows a market that has moved sharply lower from early March highs, followed by uneven attempts to stabilise.
Gold began the month at elevated levels, with 24-karat prices above Dh640 per gram, before entering a sustained correction phase. Prices slipped through mid-March, falling steadily from above Dh600 to the high Dh500 range within days.
The decline accelerated as the month progressed, with gold dropping below Dh550 and briefly touching the low Dh520s. Recent sessions have seen choppier movement, with short bursts of recovery followed by renewed dips, leaving prices well below earlier peaks but showing signs of tentative support.
That pattern reflects a market still adjusting to shifting macro signals, with no clear directional trend in the short term.
Global cues shape local pricing
International markets remain the key driver behind local price movements. Gold recovered some ground after a sharp drop in the previous session, as developments around the US and Iran conflict introduced fresh uncertainty.
Bullion traded near $4,400 an ounce in early deals after losing almost 3% earlier, when doubts emerged around a potential ceasefire. The US signalled a delay in potential military action, offering temporary relief to markets that had been reacting to escalating tensions.
Oil prices eased during the same period, helping reduce immediate inflation concerns and providing some support to gold.
Inflation and rates keep pressure on gold
Despite the rebound, the broader backdrop remains challenging for bullion. Rising energy prices continue to feed into inflation expectations, pushing bond yields higher and strengthening the dollar.
Since the conflict began, gold has fallen close to 17%, moving alongside equities and reacting inversely to oil in recent sessions. The shift highlights how macro factors have overtaken traditional safe-haven flows in the short term.
Central bank activity adds to volatility
Additional pressure has come from shifts in central bank behaviour. Turkey’s central bank sold and swapped around 60 tonnes of gold in the early weeks of the conflict, a move that added supply to the market and weighed on prices.
Large-scale central bank buying had supported gold’s rally in recent years, making any reversal in that trend a key factor for traders.
The current range remains below early March levels, offering some relief compared to recent peaks. At the same time, continued volatility suggests that prices could shift quickly depending on developments in oil markets, interest rate expectations and geopolitical signals.
The next direction for gold will depend on how these factors evolve, with short-term moves likely to remain sensitive to changes in global risk sentiment and energy prices.
- With inputs from Bloomberg.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.