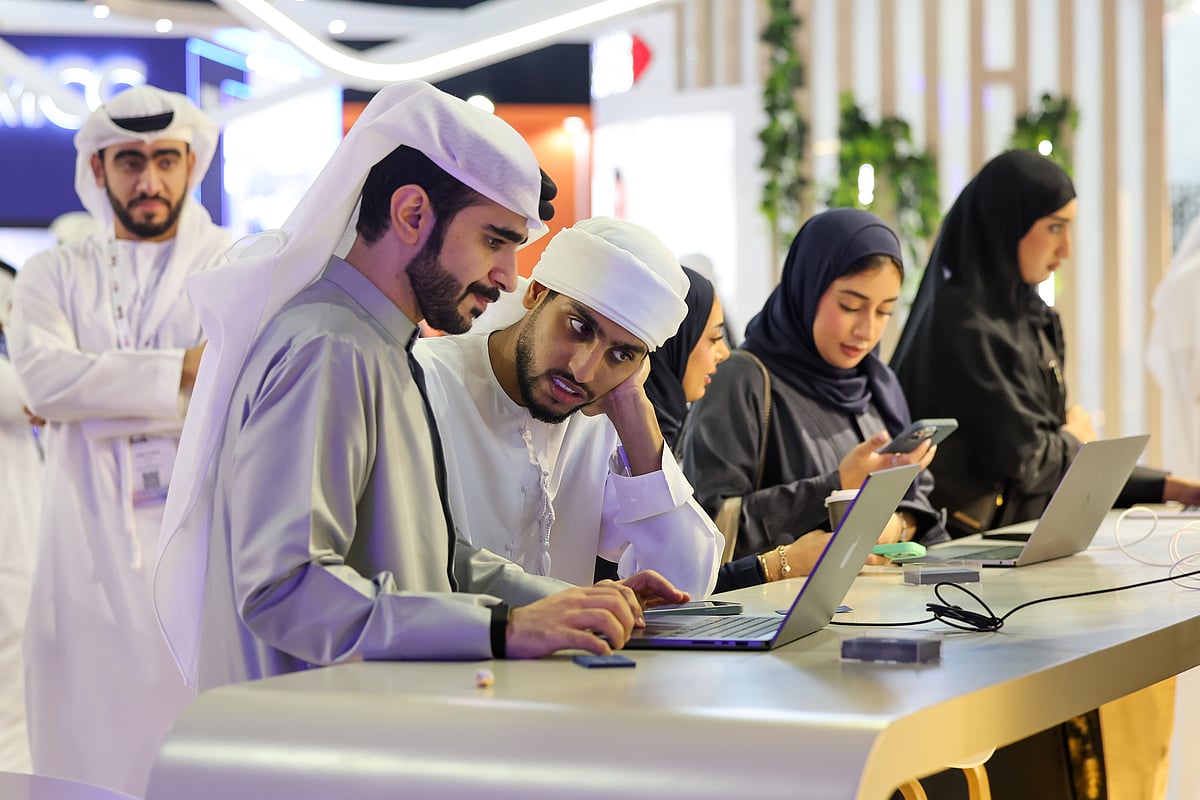
Dubai: The UAE’s non-oil private sector recorded its strongest improvement in four months during July, with new orders growing at their fastest pace since February and companies resuming hiring after cutting jobs in June.
The seasonally adjusted S&P Global UAE Purchasing Managers’ Index rose to 52.7 in July from 50.8 in June, when it had fallen to its lowest level in more than five years.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
The latest reading indicated a moderate improvement in business conditions, supported by easing regional tensions, stronger customer spending and demand linked to domestic infrastructure projects.
New orders reach five-month high
Businesses reported a gradual recovery in customer confidence during July, although tight client budgets and intense competition continued to limit demand for some companies.
Export orders increased for the first time since March, with firms linking the improvement to stronger activity across the region. The rise was modest but represented the fastest expansion in export business for a year.
Outstanding work accumulated at the strongest rate in four months, reflecting increased customer demand and supply constraints caused by freight congestion.
Companies increased output in response, with the rate of growth accelerating slightly during July but remaining below its historical average.
Hiring returns after June decline
Employment returned to growth after companies reported their steepest reduction in workforce numbers in nearly six years during June.
Businesses that recruited additional staff in July largely attributed the decision to stronger demand.
Confidence about future output weakened for a third consecutive month and fell to its lowest level since March. Only 7% of surveyed firms expected their output to increase over the coming year.
“Still, the volatile situation in the Strait of Hormuz continues to make the future uncertain and kept price pressures elevated in July, which firms struggled to fully pass on to customers amid a competitive business environment," said David Owen, Principal Economist at S&P Global Market Intelligence. "Firms also saw a reduction in inventories despite a sharp rise in purchasing, suggesting they are still operating with tighter stock volumes and longer supply schedules.”
Supply delays reduce stock levels
UAE businesses increased their purchases of raw materials and other inputs at a robust rate in July, but inventory levels contracted at their fastest pace since December 2025.
Companies linked the decline in stocks to continuing delays affecting imported deliveries and shortages of materials.
Delivery times improved modestly, partly because of smoother shipping movements through the Strait of Hormuz, although the improvement was weaker than in June.
Input cost inflation remained elevated and moved closer to the recent peak recorded in April. Around 10% of companies reported paying more for fuel, food, fertilisers, software and shipping.
Staff costs increased at their fastest pace since February, although the overall rise remained marginal.
Businesses raised their selling prices again during July, but the increase was mild because competition restricted their ability to pass higher costs to customers.
Dubai new orders strengthen
Dubai’s PMI increased to 51.7 in July from 50.7 in June, mainly because of a recovery in new business.
Companies reported the strongest increase in new orders since March as customer demand improved. Business activity continued to expand, although the rate of growth was the weakest recorded since June 2021 due to price pressures and intense competition.
Confidence about future output fell to a four-month low, while businesses reported a solid rise in input costs and a moderate increase in selling prices.
Hiring recovered slightly after Dubai companies reduced employee numbers in June for the first time in 15 months.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.