Etihad Credit Bureau launches Score 3i credit scoring model for UAE residents
36-month credit behavior now part of UAE's revamped credit scoring system
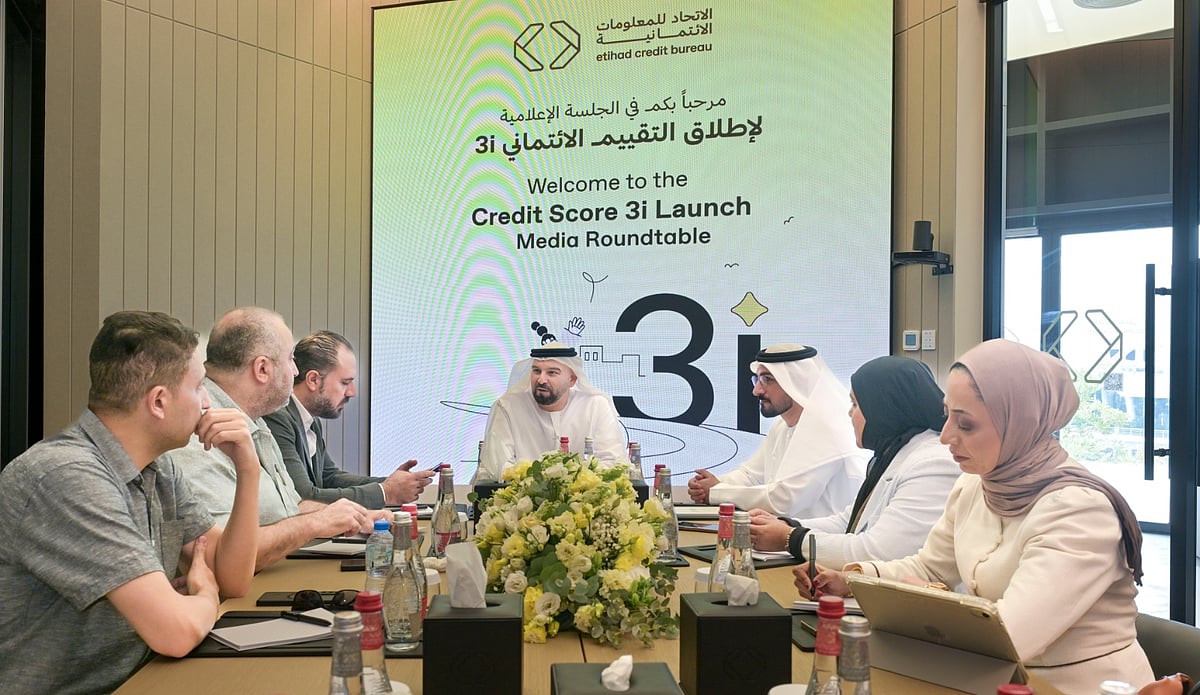
Abu Dhabi: Etihad Credit Bureau has introduced Score 3i, the third generation of its credit scoring model for UAE residents.
The model now looks at 36 months of credit behavior instead of 24, and it shows consumers the positive and negative factors behind their score in the bureau’s app and website.
“This score is actually going to be as a game changer for the industry,” said Marwan Ahmad Lufti, Director General of Etihad Credit Bureau.
The changes mainly help two groups. Consumers who have defaulted can leave the lowest score range after six months of proper payments and often rebuild within six to 12 months.
Residents who are new to credit or new to the country can get an initial score within a month, capped at 650, based on non-banking information. The full 300-850 range opens up after three to four months.
It also counts buy-now-pay-later and short-term loan payments, including those to Tabby, Tamara and Cash Now.
Built from the ground up for the UAE
Score 3i follows the bureau’s first-generation score, launched in 2018, and a second generation after it. Unlike a refresh of the existing model, the new version was rebuilt around UAE market demographics and dynamics.
Lufti said it also draws on consumer feedback, particularly about how people can recover after a default.
“Our intention is always not to penalize more than actually how to support. And I think that was one of the main issues that we sort of received or at least learned more repetitively.”
The Etihad Credit Bureau says the new model is tailored to the UAE and uses 36 months of credit behaviour.
It lets people who recover from a default begin moving out of the lowest score range sooner, potentially after six months of good payment behaviour, compared to 24 months under the previous model.
Drawing on a broader range of indicators related to financial obligations and repayment patterns, this extended assessment period provides a more comprehensive view of how credit behaviour evolves over time, supporting a better understanding of credit profiles and more informed risk assessments.
According to Lufti, this initiative is intended to make sure the process is easy on people.
“People do not need to reach out to us. We created score factors, which are live factors that are built to read what are the most important things that are impacting the score.”
Through the bureau’s app or website, consumers can now see the factors behind their score, including both positive and negative influences, in real time.
Broader coverage of everyday borrowing
The enhanced model will give banks, financial institutions and eligible fintechs fuller credit data for risk assessment, and may also serve government, regulatory, SME and real estate needs, subject to data access rules. Lending decisions will still rest with individual lenders.
The bureau announced Score 3i at a media briefing held alongside the soft opening of its new walk-in office. The redesign aims to make scores easier to understand, give people a clearer path back after financial setbacks, and open the system to residents with no banking credit history.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.