Dubai gold prices ease to Dh488.25 while market holds a narrow November range
Prices ease after mid-month rally, tracking global bullion moves and shifting Fed signals
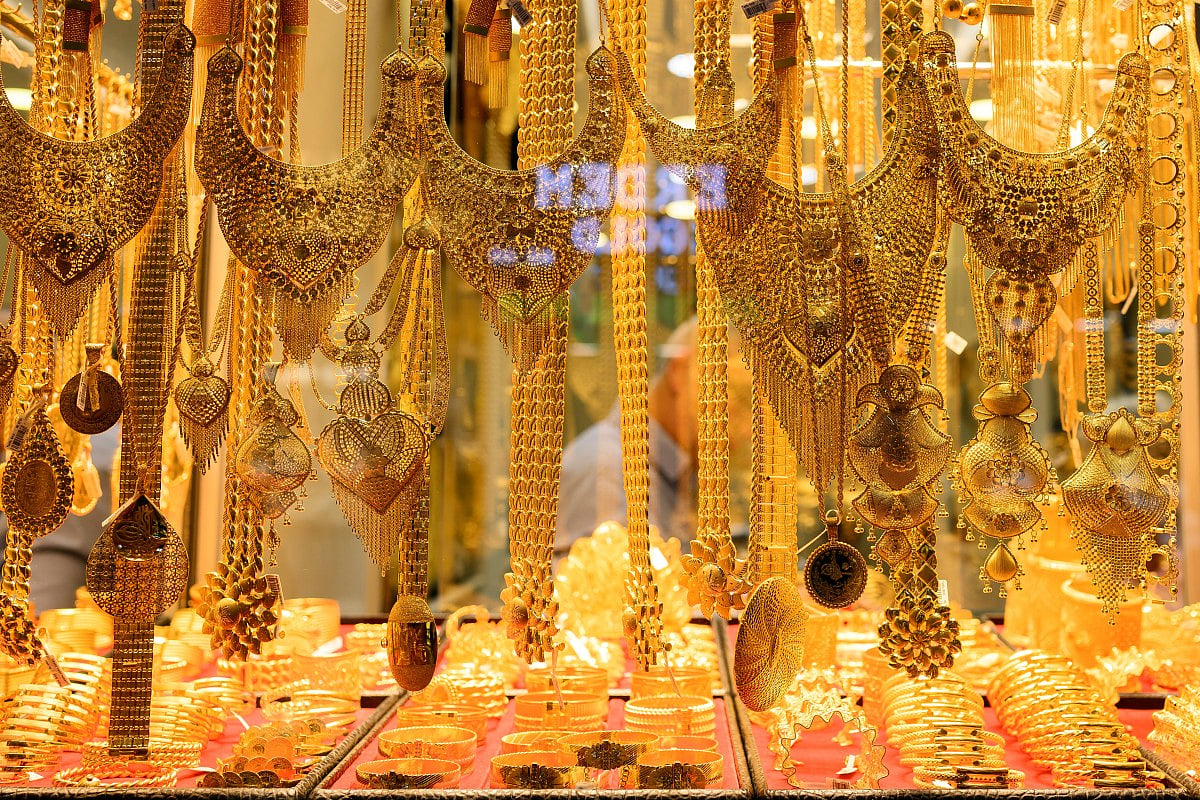
Dubai: Dubai’s gold market eased on Friday, with 24K slipping Dh3.75 from the previous session to Dh488.25 a gram. The 22K category followed the same trend, declining from Dh455.50 on Thursday to Dh452.25. The pullback comes after a month defined by tight movements, even as global bullion prices swung on shifting expectations around US monetary policy.
Prices remain confined to Dh475–Dh505
Retail rates for 24K opened November at Dh482.25 and have largely stayed within a Dh475 to Dh505 band. The lowest point came on November 4 when 24K touched Dh475.25, reflecting a brief dip in international prices and a stronger dollar. A rally then carried Dubai rates back toward Dh504.75 on November 12, mirroring the global uptick fuelled by safe-haven demand and a pause in dollar strength.
From there, prices eased again, slipping into the high Dh480s by mid-month before stabilising at Dh489.75 on November 18 and 19.
The month’s trajectory broke into three distinct stretches. The first was a slightly shaky start, as 24K moved from Dh482.25 on November 1 to Dh475.25 by November 4, before rebounding to Dh495.50 by November 11. The second phase was a short burst of momentum, with 24K touching Dh504.75 on November 12 and Dh502.25 the next day. The third phase is the cooling-off period now in place, with prices holding between Dh485 and Dh493 as traders reassess the probability of a December rate cut.
A similar pattern has played out in 22K. It opened the month at Dh446.50, slipped to Dh440 on November 4, then climbed steadily to Dh467 by November 12. It has since eased into the mid-450s and now sits at Dh453.50. The parallel movements across both categories highlight how closely UAE retail rates continue to track global sentiment rather than local demand alone.
Global bullion loses momentum
International bullion was on track for a small weekly decline. Prices fell to around $4,065 an ounce on Friday, down about 0.5% for the week. A mixed US jobs report offered little new incentive for the Federal Reserve to shift policy. Job growth beat expectations in September, but unemployment also edged higher.
Minutes from the Federal Open Market Committee’s October meeting, released on Wednesday, showed many Fed officials leaning toward keeping interest rates steady. Swap traders now see only a 40% chance of a cut next month, down sharply from expectations just two weeks ago. Bullion typically underperforms in a higher rate environment.
A strong year despite the cooldown
Despite its recent pullback from last month’s record, gold remains up around 55% this year and is on course for its best annual performance since 1979. The rally has been supported by inflows into exchange-traded funds and strong central-bank buying. But analysts say the latest surge had begun to look overstretched, driven in part by the “debasement trade”, a retreat from sovereign debt and major currencies.
Dubai’s retail prices now reflect a market that is steadying after a volatile global run, with traders watching how US data and Fed signals shape the remainder of the year.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.