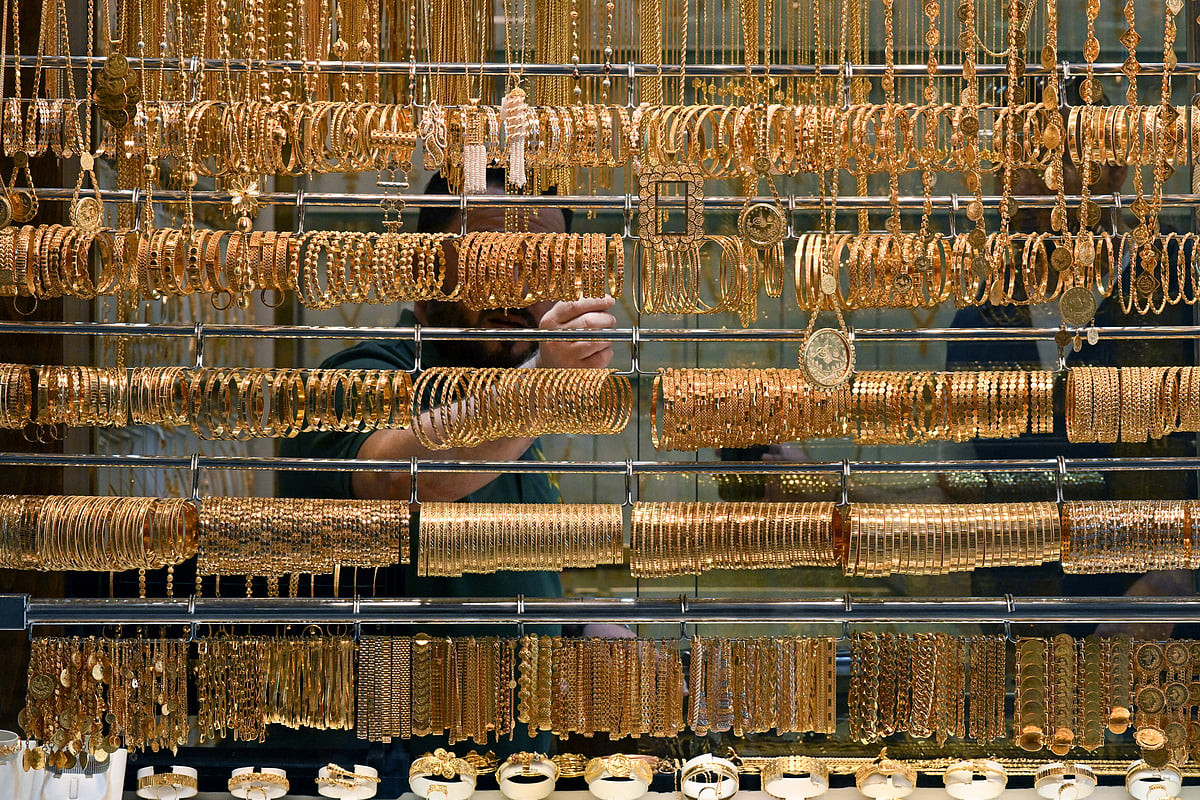
Dubai: Gold prices in the UAE edged higher on Thursday morning, tracking global gains as investors shifted money into safer assets amid escalating conflict in the Middle East and fresh volatility in currency markets.
In Dubai, the price of 24-karat gold reached Dh623.25 per gram at 9.56 am, up from Dh619.25 on Wednesday. The 22-karat variety climbed to Dh577 per gram compared with Dh573.50 a day earlier, extending the recent upward trend in local jewellery markets.
Stay updated: Get the latest faster by downloading the Gulf News app - it's completely free. Click here for Apple or here for Android. You can also find it on the Huawei AppGallery.
Movement in local prices mirrored developments in global bullion markets where investors increased exposure to precious metals while geopolitical risk continued to rise.
Global gold climbs as conflict deepens
Internationally, bullion pushed higher after the US dollar weakened and the conflict involving the United States, Israel and Iran entered its sixth day without signs of easing.
Gold rose as much as 0.9% to move above $5,180 an ounce, following a 1% advance in the previous session. Investors turned to the metal amid growing concerns over the widening military confrontation and potential disruptions to global energy supplies.
US and Israeli forces continued strikes on Iranian targets, while Tehran launched missile attacks across several countries in the region and targeted key energy infrastructure. Shipping concerns intensified after the Strait of Hormuz, a critical oil transit route, was effectively blocked during the escalation.
Washington signalled confidence in its military operations, with President Donald Trump expressing support for the campaign while American forces reportedly sank an Iranian warship in international waters. Tehran rejected reports that its intelligence ministry had approached Washington for negotiations, calling them “pure falsehood”.
Also Read
Dubai gold prices rebound after sharp sell-off unsettles global marketsDubai gold prices climb again. Global tensions reshape buyer decisionsDubai gold surges to one-month high as geopolitical tensions grip marketsTrade tensions add another layer of uncertainty
Market nerves also reflected the potential for renewed global trade disruption. Washington is preparing to introduce higher import tariffs, adding another layer of uncertainty for investors already navigating rising geopolitical risk.
Treasury Secretary Scott Bessent said that the administration’s plan to raise the universal tariff rate from 10% to 15% could take effect this week, although the European Union is expected to be exempt from the increase.
Energy prices have surged alongside the conflict, raising concerns about supply shocks that could ripple through global trade and inflation.
Dollar moves support gold demand
Currency movements have also played a role in the recent rally. Gold gained additional support after the US dollar posted its largest drop in roughly three weeks.
A weaker dollar typically lifts bullion because it makes the metal cheaper for buyers using other currencies. A widely tracked gauge of the US currency slipped about 0.4% over the past two days even though it still remains nearly 1% higher for the week.
Earlier strength in the dollar and a broad selloff in equities triggered a sharp drop in precious metals earlier this week. Markets quickly stabilised after investors unwound heavily crowded positions.
Gold has already gained roughly 20% this year amid persistent geopolitical tensions and global trade uncertainty. The metal reached an all-time high above $5,595 an ounce in late January, reinforcing its role as a defensive asset during periods of instability.
- With inputs from Bloomberg.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.