Dubai gold prices rebound after sharp sell-off unsettles global markets
Gold recovers in Dubai and globally after a rapid sell-off rattles investors
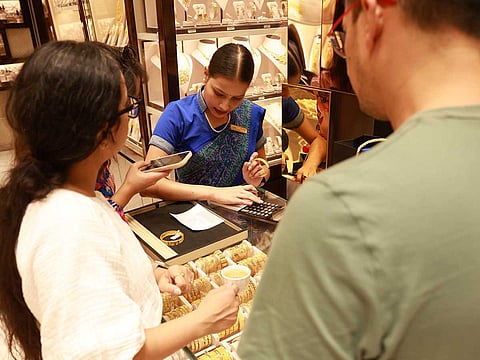
Dubai: Gold prices in Dubai staged a sharp recovery early Tuesday, after a dramatic two-day slide that followed one of the strongest rallies on record. At 8.20 am, 24-karat gold was priced at Dh579 per gram, up from Dh564.25 on Monday, while 22-karat gold rose to Dh536 from Dh522.50. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
The rebound mirrors a broader move across global markets, where bullion clawed back losses after an abrupt unwinding of speculative positions sent prices tumbling. Spot gold climbed as much as 4.2% to trade above $4,855 an ounce, following a 4.8% drop in the previous session. Silver also surged, rising as much as 8.1% to top $85 an ounce after a steep fall a day earlier.
Volatility shakes even seasoned traders
Last month’s surge in precious metals caught many investors off guard, with gold and silver racing to record highs in a matter of weeks. The rally was fuelled by rising geopolitical unease, fears of currency debasement, and growing debate over the future independence of the US Federal Reserve. Heavy buying from Chinese investors added momentum, accelerating the move to historic levels.
That dynamic shifted abruptly on Friday when the US dollar strengthened, triggering a wave of profit-taking. The pullback proved severe, with gold falling 13% in just two days, marking its sharpest short-term decline in more than a decade.
China’s demand in focus
Market attention is now firmly on China, where investor behaviour could shape near-term price direction. Over the weekend, buyers crowded into Shenzhen, home to the country’s largest bullion marketplace, to purchase gold jewellery and bars ahead of the Lunar New Year. Domestic markets will shut for more than a week from February 16, adding uncertainty around liquidity and price discovery.
Chinese state-owned banks have also tightened controls on gold investment products in an effort to curb volatility, a move that could temper speculative flows once trading resumes.
Bullish calls remain intact
Despite recent turbulence, some institutions continue to back higher prices. Deutsche Bank AG said in a note on Monday that it was standing by its forecast for bullion to rally to $6,000 an ounce, citing structural demand and ongoing macro risks.
Geopolitics remains another key variable. Investors are watching developments around Iran after Donald Trump said talks on a new nuclear deal could take place in the coming days. Any diplomatic progress could ease safe-haven demand and weigh on prices, while prolonged uncertainty would likely keep gold firmly in focus for investors
- With inputs from Bloomberg.