Dubai gold tops Dh630 after gaining more than Dh110 this month
Dubai gold prices hit fresh records as global demand surges and the dollar weakens
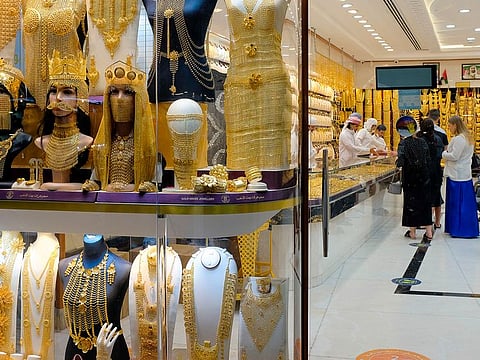
Dubai: Gold prices in Dubai surged to record levels on Wednesday, tracking a sharp rally in global bullion markets as investors moved aggressively into precious metals amid currency weakness and mounting geopolitical risks. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
By 10 am local time, 24-karat gold was priced at Dh632 per gram, up sharply from Dh611.50 on Tuesday. The 22-karat rate followed the same trajectory, climbing to Dh585.25 from Dh566.25 a day earlier.
The move marks one of the steepest day-on-day increases seen in Dubai’s retail gold market this year, reinforcing the metal’s role as a preferred store of value during periods of market stress.
Prices climb steadily through January
Gold prices in Dubai have been building momentum throughout January, with gains accelerating in the second half of the month. At the start of the year, 24-karat gold was trading just above Dh520 per gram. By mid-January, prices had crossed Dh550, before pushing past Dh600 in the final week.
The latest jump takes the metal more than Dh111.75 higher than early January levels, while 22-karat gold has risen by over Dh103.5 in the same period.
Global gold rally fuels local surge
Internationally, gold surged to a fresh all-time high above $5,200 an ounce, extending one of the strongest rallies in the metal’s modern history. Bullion rose as much as 1.3% on Wednesday, following a 3.4% jump in the previous session, its biggest one-day gain since April.
The rally has been fuelled by a sharp decline in the US dollar, combined with a broad selloff in sovereign bonds and growing unease over fiscal policy and geopolitical stability. A widely followed gauge of the dollar fell 1.1% on Tuesday, its steepest daily drop in months, making gold cheaper for buyers using other currencies.
President Donald Trump said he was unconcerned about the dollar’s decline, telling reporters that currency values were expected to fluctuate. His comments came as the greenback slid to its weakest level in nearly four years.
Investors seek safety in precious metals
Market participants say the flight into gold reflects deepening investor anxiety across multiple fronts, including geopolitical tensions, rising fiscal deficits and uncertainty over future monetary policy.
Expectations of a more dovish Federal Reserve have also played a key role. Bond traders have stepped up bets on lower US interest rates amid speculation of a leadership shift at the central bank. Lower rates typically support gold prices since the metal does not offer yield.
Central banks and funds add momentum
Gold’s surge has also been supported by strong central-bank buying and sustained inflows into bullion-backed exchange-traded funds. Options markets reflect growing confidence in higher prices, with implied volatility on Comex futures reaching levels last seen during the peak of the Covid-19 market turmoil in 2020.
Other precious metals have followed gold higher. Silver climbed nearly 3% and is approaching record levels, while platinum and palladium also advanced. Heightened volatility has prompted margin increases on silver futures and temporary trading halts in some Asian silver funds.
- With inputs from Bloomberg.