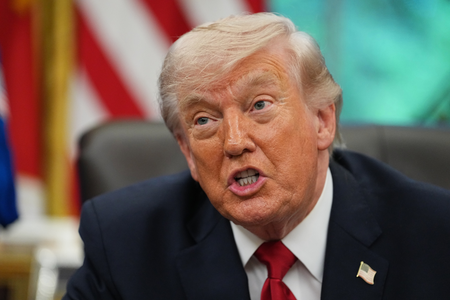
Dubai: US President Donald Trump has welcomed the UAE’s decision to leave OPEC, saying the move could help bring down oil and fuel prices at a time when the Iran war has kept energy markets under pressure.
“I think it’s great,” Trump told reporters at the White House on Wednesday when asked about the UAE’s decision.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
“I think ultimately it’s a good thing for getting the price of gas down, getting oil down, getting everything down,” he added. “They’re having some problems in OPEC.”
The UAE announced on Tuesday that it will leave the Organisation of the Petroleum Exporting Countries and the wider OPEC+ alliance effective May 1, 2026. The decision ends nearly six decades of UAE participation in coordinated oil production policy and gives the country more freedom to set output based on its own capacity plans and market conditions.
The move comes at a sensitive time for global energy markets. Oil prices have stayed elevated because of the Iran war, while restrictions around the Strait of Hormuz have added pressure to shipping and supply routes. Any change in production policy from a major Gulf producer is likely to be watched closely by traders, governments and consumers.
The UAE joined OPEC through Abu Dhabi in 1967 and remained part of the group after the federation was formed in 1971. It has since been one of the key Gulf producers within OPEC, alongside Saudi Arabia and Kuwait. Middle East producers account for roughly 30% of global oil supply, making any shift in the region’s production strategy significant for the wider market.
Why did the UAE leave OPEC?
The UAE said the decision followed a comprehensive review of its production policy, current capacity and future energy plans. State news agency WAM said the move reflects the country’s national interest and its commitment to responding effectively to market needs while supporting global energy stability.
“This is a policy decision, it has been done after a careful look at current and future policies related to level of production,” he told Reuters, adding that the UAE did not raise the issue with other countries before making the decision.
The country has been investing heavily in expanding its production capacity and plans to raise output capacity from about 3.4 million barrels per day to 5 million barrels per day by 2027. Leaving OPEC and OPEC+ removes the UAE from quota agreements, giving it more flexibility to bring new capacity to market when it chooses.
In an interview with CNBC, Al Mazrouei said the decision followed “a very careful and long review” of policy.
The decision to be outside any constraint is something that important for us to ensure that we are attaining at the market condition, at the right time and at the right pace,” he said.
He added that the timing was chosen to limit disruption to prices.
“We believe that the world is currently under supplied, and our exit at this time is the right time for it, because it will have a minimum impact on the price.”
Speaking to CNN, Al Mazrouei linked the timing to current shipping restrictions in the region.
“Timing is right because it will not significantly impact the market and the price because the Strait of Hormuz is closed and restricted,” he said, describing the move as a “sovereign national decision.”
Dr Sultan Al Jaber, Minister of Industry and Advanced Technology and ADNOC CEO, said the decision reflects a sovereign approach aligned with the UAE’s long-term strategy and market stability.
The UAE has said it continues to value its long-standing cooperation with OPEC, but the current phase requires faster decision-making and more room to respond to changes in global demand. Al Mazrouei said the country remains committed to working with other producers to support energy security.
Sign up for the Daily Briefing
Get the latest news and updates straight to your inbox
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.