Global energy power shifts towards Middle East as 72% of industry leaders predict bigger role
ADIPEC report reveals how geopolitical tensions, investment and AI are reshaping energy
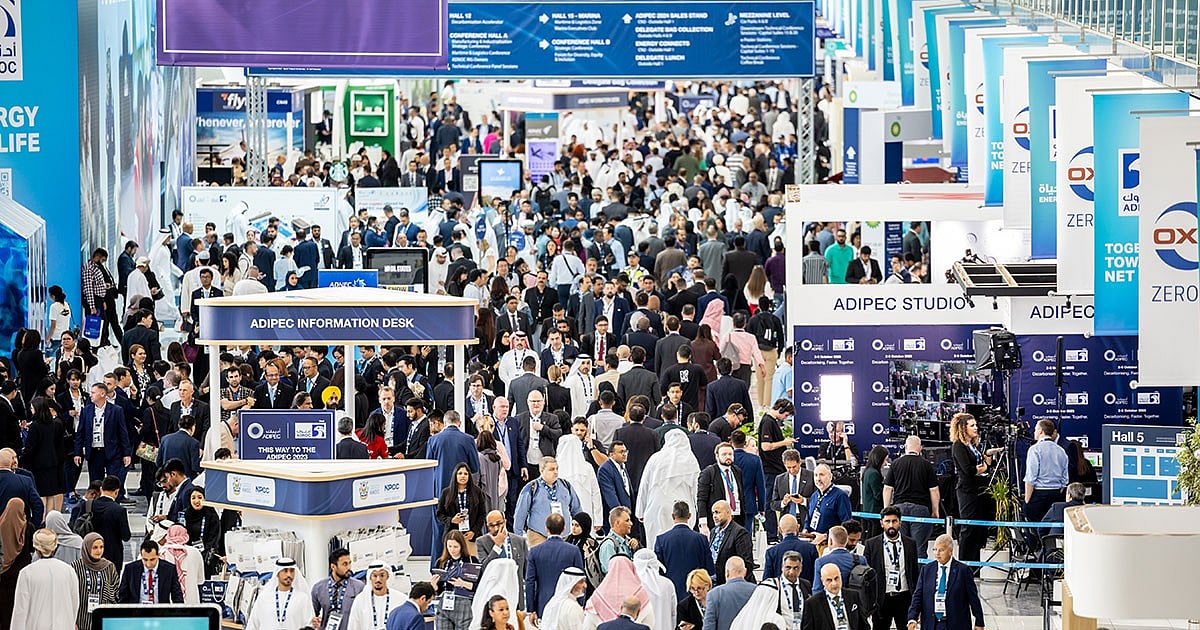
The year 2026 marks a historic turning point for the global energy ecosystem. Following one of the most severe geopolitical stress tests in fifty years—including severe disruptions in key transit corridors like the Strait of Hormuz, which at its peak removed roughly 14% of global oil and gas supply—the global energy system has demonstrated remarkable resilience.
Rather than collapsing under shock, 64% of global energy insiders state that the system proved more resilient than expected. This adaptability stems not from chance, but from proactive structural shifts: rapid trade re-routing, digital integration, market diversification, and deep strategic realignment.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
Three defining dynamics dominate the 2026 outlook:
The Eastward Migration of Influence: The global center of gravity for energy demand, investment, and strategic decision-making has moved decisively toward the Middle East and Asia.
Re-Defining Energy Security as Diversification: Energy independence through isolation is obsolete; modern energy security requires an "all-of-the-above" multi-source strategy.
The Artificial Intelligence Demand Surge: AI is acting as both a technology enabler and a major new energy consumer, driving electricity demand forecasts significantly higher.
Deep-dive research analysis
1. Geopolitical Realities & The Energy Trilemma
While 77% of executives remain optimistic and 85% highlight increased investment attractiveness, the sector operates under severe strain.
The Security Imperative: Conflict and war rank as the primary sector threat for 42% of general energy decision-makers and 55% of oil and gas specialists. Tariffs/supply chain friction (24-31%) and climate disruption (25-26%) follow.
Diversification vs. Self-Reliance: Only 20% of leaders rank domestic self-reliance among their top priorities for energy security. Instead, security is defined by expanding supply options, building redundant routes, protecting critical infrastructure (34%), and investing in renewables (37%) and gas.
Energy Source Trajectory: Over the next decade, net expectations show increased importance across nearly every source: Renewables (83% net), Natural Gas/LNG (72% net), Nuclear (69% net), and Oil (62% net). Coal remains globally divided (25% net), showing positive expansion outlooks in Asia/Middle East but negative trajectory in Europe (-3%).
2. The Gulf-Asia Corridor: Global Energy's New Center of Gravity
Energy trade, capital deployment, and demand growth have re-anchored along the Gulf-Asia Corridor.
Regional Dominance: The Middle East was selected as the #1 regional opportunity overall (30%) and ranked second in every other region worldwide. 72% of respondents expect the region's global importance to rise significantly over the next decade.
Supplier-Customer Alignment: 49% of oil and gas producers cite Asia Pacific as their primary customer market, closely matched by the Middle East (48%). Conversely, consumers identify the Middle East and Asia Pacific as their primary critical suppliers.
The Asian Divide:
Growth Asia (India & Indonesia): Boasting extreme optimism (86% and 94% respectively), focused on expanding infrastructure and generating rapid baseline capacity.
Import-Dependent Asia (Japan & South Korea): Exhibiting high caution (Japan optimism sits at 23%), heavily prioritizing route protection, reserves, and supply security.
Nuclear Convergence: Nuclear energy emerges as the unifying baseline technology across Asia, supported by 84% in India, 77% in Indonesia and South Korea, and 63% in Japan.
3. Artificial Intelligence: Re-Drawing Power Balances and Demand
Artificial Intelligence is fundamentally altering both operational efficiencies and baseline power infrastructure.
Power Shift to Tech: 43% of energy executives believe Technology and AI firms will hold more influence over the energy industry than governments (15%), financial institutions (15%), or traditional energy giants (14-9%).
Demand Reality Check: 81% expect AI-driven electricity demand to surge past official forecasts (32% expecting demand to be "much higher"). Global data center power consumption is projected by the IEA to reach 950 TWh by 2030.
Pragmatic Adoption Barriers: While 71% see AI as a net opportunity, industry practitioners highlight significant operational bottlenecks:
Legacy System Integration: 83% of AI-focused oil/gas leaders cite difficulties interfacing with legacy infrastructure.
Data Plumbing: Unstructured, non-standardized data across decades-old assets presents the largest adoption hurdle (21% open-text responses).
Near-Term Overestimation: 57% of AI optimists acknowledge that short-term demand impact is currently hype-driven, despite vast long-term structural impact.
4. Capital, Infrastructure, and Execution Constraints
Despite a record $3.4 trillion in annual global energy investments ($2.2T clean/grid, $1.2T oil/gas/coal), capital allocation faces a race against time.
Execution Speed Over Capital Availability: The primary industry barrier is no longer raising capital, but deploying infrastructure at a speed that matches demand.
Critical underinvestment areas:
Energy Insiders: Highlight Renewable Generation (34%), Energy Storage (31%), Grids & Transmission (24%), and Nuclear (24%) as severely underfunded.
Oil & Gas Insiders: Point to Carbon Capture / Low-Carbon Fuels (38%) and Grids & Transmission (35%) as their top investment deficits.
Decarbonization Through Integration: Decarbonization has shifted from a philosophy of asset retirement to one of operational integration. 46% of oil and gas leaders rank low-carbon fuel/hydrogen innovation as the top deliverable to meet future demand, while 38% focus on lowering baseline extraction emissions.
Strategic Conclusion: The Execution Era
The findings of the ADIPEC Global Energy Report 2026 confirm that the energy transition is not a simple linear trade-off between fossil fuels and renewables. It is a complex expansion of a multi-source, digital-first, globalized energy system.
Having survived severe geopolitical stress tests, the industry has proven its resilience. As capital, technology, and geopolitical weight consolidate along the Gulf-Asia axis, the sector's central challenge over the coming decade is no longer formulating ambition, but executing delivery.
Key statistics
64% say the global energy system proved more resilient than expected.
72% expect the Middle East to become more important in global energy over the next decade.
85% say energy is a more attractive sector for investment than five years ago.
93% say meeting future energy demand will require growth across multiple energy sources
rather than one dominant source.
77% are optimistic about the decade ahead
*. (Source: ADIPEC Global Energy Trends 2026)
Network Links
GN StoreDownload our app
© Al Nisr Publishing LLC 2026. All rights reserved.