Dubai gold prices drop for 14th day as war and rate fears drive sell-off
Steep March decline deepens as inflation risks and rates outlook weigh on gold
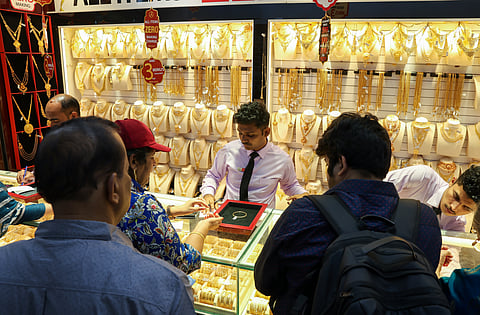
Dubai: Gold prices in Dubai slipped again on Tuesday morning, extending a sharp run of declines that has kept buyers cautious and traders focused on how far the correction could run. At 8:30 am, the 24-karat rate dropped to Dh523.25, down from Dh530.75 a day earlier, while 22-karat gold fell to Dh484.75 from Dh491.50. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
Sharp reversal from early March highs
The trend shows a steady erosion in prices from the start of the month, when 24-karat gold was trading well above Dh620 and briefly approached Dh640 levels. Since then, each successive session has chipped away at gains, with the decline accelerating after mid-March.
Stay updated: Get the latest faster by downloading the Gulf News app - it's completely free. Click here for Apple or here for Android. You can also find it us on the Huawei AppGallery.
By March 17, 24-karat gold was still hovering near Dh600. Within days, it slipped below Dh560, then Dh540, before breaking under Dh530 and now moving closer to Dh520. The pace of decline has been consistent, with only brief pauses failing to reverse the direction.
A similar pattern has played out across other purities. The 22-karat rate has fallen from above Dh580 in early March to the mid-Dh480 range, while 18-karat gold has dropped from around Dh470 to below Dh400, reflecting a broad-based correction across the market.
War-driven volatility shifts market behaviour
The sell-off comes amid heightened volatility linked to developments in the Middle East. Gold briefly found support on safe-haven demand but has since come under pressure as investors reassess inflation risks and interest rate expectations.
Bullion has fallen sharply in recent sessions, marking one of its longest losing streaks on record, with price movements closely tracking swings in oil and equity markets.
Inflation fears and rates outlook weigh on gold
Rising energy prices have emerged as a key driver behind the shift in sentiment. Higher oil costs are fuelling inflation concerns, which in turn are pushing expectations that central banks may keep interest rates elevated or even tighten further.
That dynamic is weighing on gold, which does not offer yields and tends to lose appeal when borrowing costs rise.
“Gold is currently caught between two opposing forces. While geopolitical tensions would support demand for safe-haven assets, the inflationary impact of rising energy prices is driving expectations of higher interest rates, which is weighing heavily on gold,” said Jakub Rochlitz, Market Analyst at eToro.
“What we are seeing resembles a classic liquidation phase, with investors taking profits after last year’s strong rally and repositioning in response to changing macro conditions.”
Looking further ahead, the long-term outlook for gold has not been entirely undermined. Its performance will depend on how the geopolitical situation evolves, how inflation trends develop, and how central banks respond.
Liquidation phase gathers pace
Market positioning has also amplified the decline. After months of strong gains, gold had become a crowded trade, leaving it vulnerable when investors began raising cash.
Ole Hansen, Head of Commodity Strategy at Saxo Bank, said the current environment is forcing a broad repricing across markets.
“Gold and silver remain under considerable pressure as the Middle East war continues to trigger a broad macro economic shock across global markets, forcing investors to reprice inflation, rates, growth, and liquidity conditions simultaneously.”
The magnitude of the correction is notable. Month-to-date, gold is down 19.4% and silver 30.9%, while year-to-date losses stand at 1.8% and 8.1%, respectively. However, on a one-year basis, gold remains up 38.3% and silver 90.0%, underscoring how strong the preceding rally had been and why the current liquidation phase is proving so intense.

He added that gold’s return to its long-term averages reflects the scale of the reversal, with selling driven by “long liquidation, stop-loss selling, and investors raising liquidity.”
What buyers should watch
Despite the sharp correction, the longer-term outlook remains tied to how the geopolitical situation evolves and how central banks respond to inflation pressures.
Short term direction will depend on whether oil prices stabilise and whether rate expectations ease. Until then, volatility is likely to persist, keeping Dubai gold buyers on the sidelines and waiting for clearer signals before stepping back into the market.
- With inputs from Bloomberg.