Buying gold in Dubai this weekend? Prices are back at August’s highest level
Dubai’s 24K rate is back at Dh514 after climbing from Dh485.50 earlier this week
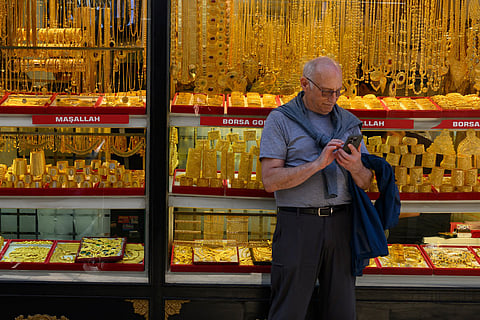
Dubai: Dubai gold prices climbed again on Friday morning, taking local rates back to their highest level so far this month and leaving shoppers facing a considerably higher price than they did at the start of August. (Check latest UAE gold prices here, alongside prices in Saudi Arabia, Oman, Qatar, Bahrain, Kuwait, and India.)
The 24-karat variety was priced at Dh514 per gram at 9.58 am, up from Dh510.50 on Thursday, while 22-karat gold rose to Dh476 from Dh472.75.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
The latest increase means 24K gold has gained Dh26.75 per gram since August 1, when it stood at Dh487.25, while 22K has risen Dh24.75 from Dh451.25 over the same period.
Prices return to Wednesday’s high
Gold began August at Dh487.25 for 24K before slipping to Dh485.50 on August 3, its lowest level so far this month. Prices then moved higher rapidly, reaching Dh492.25 on August 4 before jumping to Dh514 a day later.
Thursday brought a modest pullback to Dh510.50, but Friday’s increase returned 24K gold to Dh514, matching Wednesday’s level. The 22K variety followed a similar path, climbing from Dh449.50 on August 3 to Dh476 on August 5, easing to Dh472.75 on Thursday and returning to Dh476 on Friday morning.
The move means buyers who postponed purchases at the beginning of the month are now looking at a difference of more than Dh25 per gram for 24K gold.
Global gold heads for biggest weekly gain in six months
Internationally, bullion was heading for its biggest weekly increase in more than six months, supported by buyers entering the market after prices held above a closely watched technical level.
Spot gold rose as much as 0.7% to near $4,270 an ounce on Friday and was up more than 5% for the week. Prices briefly moved above $4,300 on Thursday amid optimism around a potential reopening of the Strait of Hormuz before those gains faded.
Fresh tensions in the Middle East had a limited immediate impact on bullion on Friday. Reports said Iran had struck “hostile targets” in the Strait of Hormuz and was seeking to bar US and Israeli vessels from passing through, while the Houthi group said it had carried out a large-scale attack against forces from Yemen’s Saudi-backed government.
Gold’s rally earlier in the week was not driven entirely by expectations of de-escalation, helping prices remain relatively steady despite the latest developments.
Chinese investors add to gold holdings
Investment demand also remained supportive, with gold-backed exchange-traded funds in China recording further inflows this week and extending their longest streak of additions since March.
Institutional investors viewed current prices as an attractive entry point, while gold’s ability to remain above $4,000 an ounce also helped maintain confidence in the metal.
Higher interest-rate expectations remain a near-term pressure on bullion because gold does not pay interest.
Traders have priced in roughly a 60% probability of a US interest rate increase in September after the Financial Times reported that Federal Reserve Chairman Kevin Warsh would be prepared to raise borrowing costs if inflation readings remain elevated in the coming weeks.
Gold remains nearly a fifth below the levels seen when the US-Iran war began in late February. The conflict pushed energy prices higher, adding to inflation pressures and increasing expectations that interest rates could remain elevated for longer.
- With inputs from Bloomberg.