Dubai gold prices surge amid US-Iran tensions and Fed uncertainty
Local rates reverse Monday’s dip while global bullion trades in a narrow range
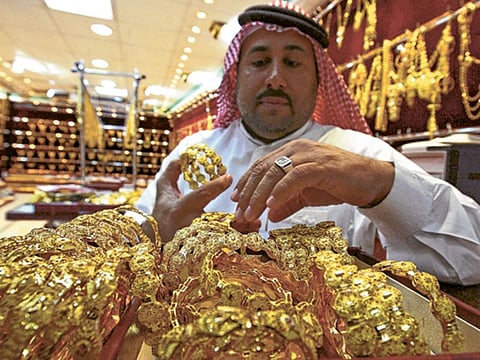
Dubai: Dubai gold buyers faced higher rates on Tuesday morning after local prices reversed Monday’s decline, with the 24-karat variety gaining Dh3.75 per gram.
The 24K rate stood at Dh489.25 per gram at 9.11 am on August 4, compared with Dh485.50 on Monday. The 22K variety rose by Dh3.50 to Dh453 per gram from Dh449.50.
Get updated faster and for FREE: Download the Gulf News app now - simply click here.
Buyers purchasing 21K gold were quoted Dh434.25 per gram, up from Dh431, while the 18K variety increased to Dh372.25 from Dh369.50.
Prices recover after Monday’s decline
Dubai gold rates began August at Dh487.25 per gram for 24K and Dh451.25 for 22K, with both varieties remaining unchanged on August 2.
Prices moved lower on Monday, when 24K gold slipped to Dh485.50 and 22K fell to Dh449.50, before recovering on Tuesday morning.
The latest increase left the 24K rate Dh2 above its August 1 level, while 22K gold was Dh1.75 higher than at the beginning of the month.
Bullion holds near $4,060
Gold traded in a narrow range globally as investors monitored diplomatic efforts aimed at cooling tensions between the US and Iran, which could push energy prices lower and reduce pressure on the US Federal Reserve to raise interest rates.
Bullion traded near $4,060 an ounce after ending Monday little changed.
President Donald Trump, after calling off an attack, described his latest offer of talks as Tehran’s “last chance” and said he expected the Strait of Hormuz to reopen fully.
Tehran denied that it was holding talks with the US but said discussions with Oman aimed at allowing more ships to move through the Strait of Hormuz were progressing.
Currency intervention adds pressure to bond markets
US and Japanese officials separately indicated that they were determined to continue defending the yen following their first joint currency intervention in 15 years.
Japan is the largest foreign holder of US Treasuries, and any bond sales used to fund efforts to support the yen could place further pressure on US government debt while inflation concerns and the Iran war continue to push yields higher.
Higher bond yields and expectations that interest rates will remain elevated typically weigh on gold, which does not provide investors with a regular yield.
Interest-rate outlook remains in focus
Gold has declined by more than a fifth since the US-Iran war began in late February, with higher energy prices adding to inflationary pressure and increasing the likelihood that interest rates will remain elevated for longer.
Federal Reserve officials kept monetary policy unchanged at their meeting last week, although three policymakers dissented in favour of an interest-rate increase.
Federal Reserve Bank of New York President John Williams said interest rates remained well positioned and that inflation should ease during the second half of the year, according to an interview with Reuters published on Monday.
- With inputs from Bloomberg.