Rupee hits record low for 6th time this month, UAE expats gain
Indian currency weakens steadily, giving dirham senders higher value
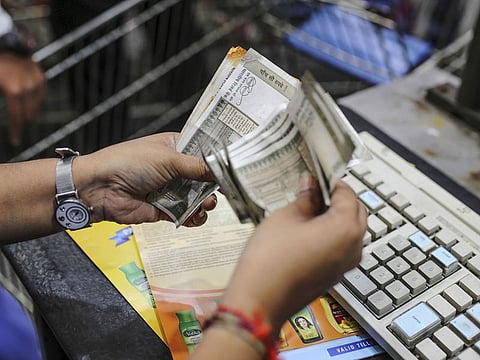
Dubai: The Indian rupee slipped to another record low against the UAE dirham on Friday, extending a month of steady declines that is reshaping remittance flows for Indian expats.
At 1:00 pm, Dh1 was equivalent to Rs25.79, marking the sixth time this month the currency has touched a fresh low. The move builds on a gradual weakening trend seen over recent sessions, with the rupee trading within a narrow but downward range.
Stay updated: Get the latest faster by downloading the Gulf News app - it's completely free. Click here for Apple or here for Android. You can also find it us on the Huawei AppGallery.
A month of repeated lows
The current slide has unfolded in stages through March, with each move pushing the rupee into new territory.
Early in the month, the currency crossed the Rs25 mark against the dirham for the first time, a level that had held for years. That shift marked a turning point in sentiment, with subsequent sessions reinforcing the downward trend.
By mid-March, the rupee had weakened further to around Rs25.25, before extending losses in the days that followed. Brief periods of stabilisation were followed by renewed pressure, lifting the rate to the mid Rs25.50 range and beyond.
The latest move to Rs25.79 reflects a continuation of that pattern, with the currency steadily losing ground over successive sessions.
What is driving the weakness
The rupee’s decline is closely linked to rising energy prices and global currency movements. India’s heavy reliance on imports makes it particularly sensitive to shifts in oil markets.
Brent crude has climbed well above $100 per barrel, far exceeding earlier assumptions, increasing the country’s import bill and raising inflation risks.
That backdrop has made Indian assets less attractive to foreign investors, triggering sustained outflows from both equities and bonds.
Overseas investors have pulled billions of dollars from local markets this month, adding to downward pressure on the currency.
Pressure builds across markets
The currency’s weakness is part of a broader shift in financial conditions. Government bond yields have climbed to their highest levels in months, reflecting concerns around inflation and fiscal pressure.
Markets are now pricing in the possibility of further interest rate increases, even as borrowing costs have already moved higher.
The Reserve Bank of India has stepped in to support the currency and bond markets, but intervention has come at a cost, with foreign exchange reserves declining.
That limits the room for aggressive action if pressures persist.
What to watch next
The direction of the rupee will depend largely on how global energy markets evolve and whether foreign investor sentiment stabilises.
Continued pressure from oil prices and capital outflows could keep the currency under strain in the near term.
At the same time, any easing in global conditions or stabilisation in flows could help slow the pace of decline.
For now, the rupee’s repeated record lows reflect a market adjusting to higher import costs, tighter financial conditions and persistent external pressures, while offering short-term gains for expats sending money home.
- With inputs from Bloomberg.