Philippine peso slides to multi-month lows against dirham, boosting UAE remittances
Peso weakens against the dirham as oil risks and inflation concerns weigh on outlook
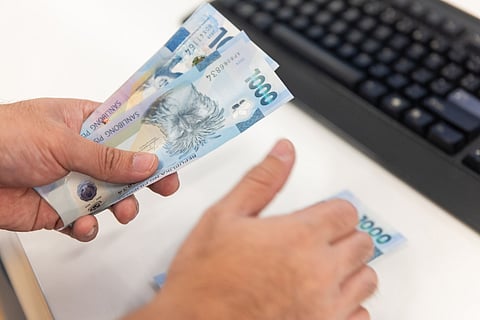
Dubai: Filipino expatriates in the UAE are finding stronger value in their remittances after the Philippine peso slipped to one of its weakest levels against the UAE dirham in recent months, pushing the exchange rate to around Dh1 for 16.17 pesos on March 9.
Currency movements over the past several weeks show a steady climb in the dirham’s purchasing power against the Philippine currency, a trend that has improved remittance value for thousands of overseas workers sending money home.
Data indicate that a dirham purchased roughly 15.6 pesos in late February, then gradually strengthened through the first week of March. Rates moved past 15.8 pesos in early March and approached the 16 mark within days. By March 8 and 7, the rate stood close to 15.99 pesos, before climbing further to 16.17 pesos on March 9.
Earlier in the period, the dirham hovered largely in the mid-15.7 range through mid-February, with several sessions around 15.72 to 15.75 pesos, indicating a gradual but persistent depreciation of the Philippine currency across the month.
Stay updated: Get the latest faster by downloading the Gulf News app - it's completely free. Click here for Apple or here for Android. You can also find it on the Huawei AppGallery.
The move reflects a combination of global pressures that have pushed the peso weaker against major currencies, particularly the US dollar, which indirectly influences the dirham because of its dollar peg.
Oil risk adds pressure on the peso
Energy markets have emerged as a major factor behind the peso’s recent weakness.
According to the Bangko Sentral ng Pilipinas, a sharp rise in crude oil prices could trigger renewed inflation pressures and potentially force policymakers to tighten monetary policy.
Governor Eli Remolona Jr. warned that a significant surge in global oil prices could push inflation beyond the central bank’s tolerance range.
“It’s possible that at $100 a barrel, we will begin to breach what we call our tolerance range” of 4% inflation, Remolona said in an interview with Bloomberg Television.
Oil prices have already climbed roughly 10% since the escalation of conflict in the Middle East, a move the central bank currently considers manageable. A sharper jump would have wider consequences for the Philippine economy because higher fuel costs quickly feed into transportation, food prices and imported goods.
“If oil prices rise sharply, persistently, then we have work to do,” Remolona said.
Inflation outlook complicates policy path
Recent economic indicators suggest inflation pressures could begin building again after a relatively stable period earlier this year.
Consumer prices in the Philippines rose 2.4% in February, the fastest pace recorded in more than a year. The reading still sits within the central bank’s 2% to 4% target range, though economists warn that prolonged disruptions to global energy supply could push inflation higher in the coming months.
Economic growth has also softened. Fourth quarter expansion slowed to roughly 3%, well below the country’s estimated potential growth range of 5.5% to 6%. Remolona described the situation as a “vicious circle” where weak confidence weighs on growth while slow growth further erodes sentiment.
The central bank has already cut its key policy rate by 225 basis points since August 2024, signalling the easing cycle could soon reach its end if inflation risks intensify.
- With inputs from Bloomberg.